Swaps data: Sonia growth spreads down the curve
New figures show boom in sterling OIS swaps is not limited to short-dated trades
Last month’s article looked at some of the products that – if regulators have their way – will replace Libor-linked instruments before Libor itself can die. It was a popular piece, but the analysis was hampered by the absence of recent data on global cleared swap volumes by tenor. On its face, rapid growth in Sonia-referencing interest rate swaps looked encouraging – but to say how encouraging, you’d need to see liquidity propagating along the curve, rather than pooling exclusively in the shortest tenors.
As luck would have it, I have since managed to get my hands on such data – so, let’s go back and take a closer look.
Sonia swaps
In sterling, the Bank of England took over as the administrator of Sonia in April 2016. Two years later, it reformed the benchmark by including bilaterally negotiated transactions alongside brokered transactions, with a resulting three-fold increase in the underlying population, averaging £50 billion ($65.4 billion) daily.
At the same time, the working group on sterling risk-free reference rates selected Sonia as its preferred benchmark and has been working to catalyse a broad-based transition to Sonia. Let’s see what the data reveals about the progress so far.
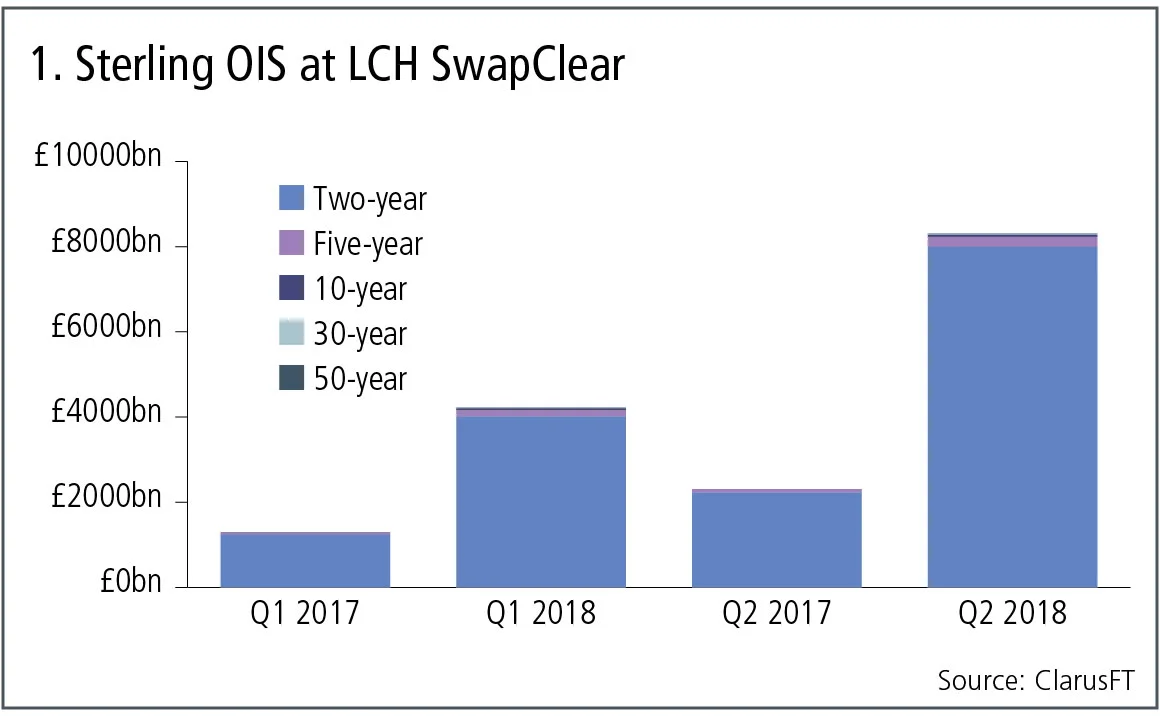
Figure 1 shows:
- Large increases, comparing quarters in 2018 with a year earlier.
- The first quarter of 2018 with £4.2 trillion gross notional, massively up from the first quarter of 2017.
- The second quarter of 2018 with £8.3 trillion gross notional, also much higher than the year-earlier quarter.
- Volumes massively dominated by tenors below two years, but larger slivers for tenors between two- and five-year and above starting to become visible in this year’s data.
Let’s exclude the sub-two-year bucket and focus on volume in the longer tenors.
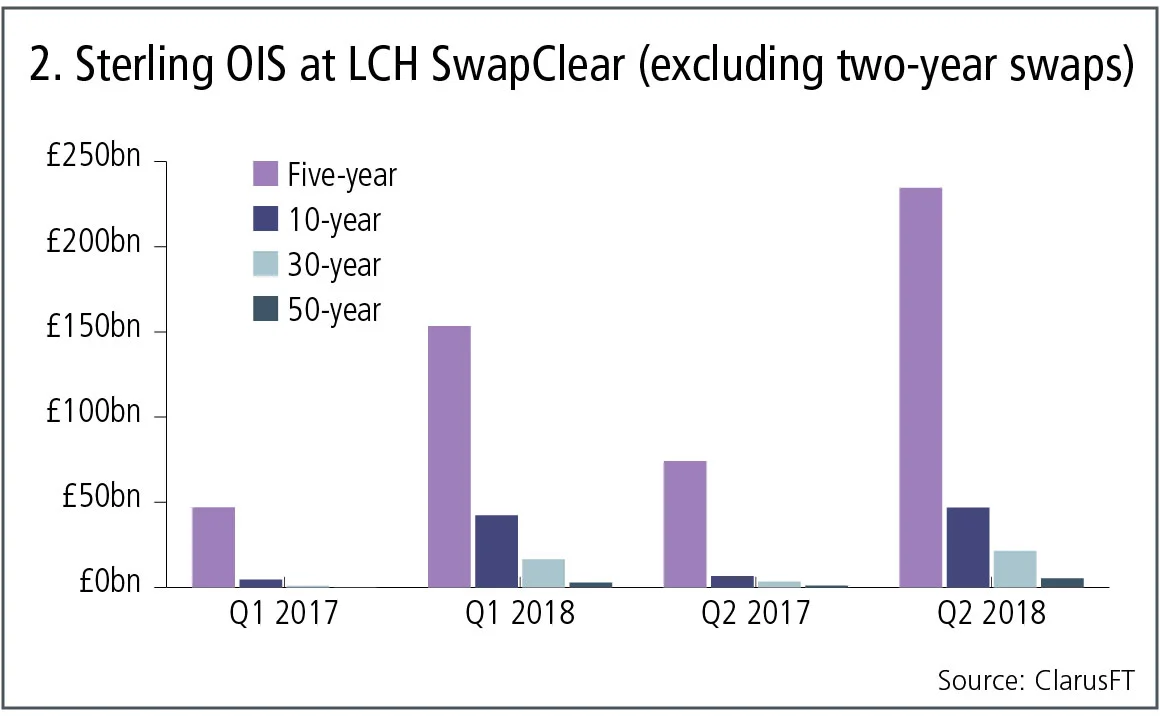
Figure 2 shows:
- The two- to five-year tenor showing strong growth and volumes reaching £235 billion in the second quarter of 2018.
- The five- to 10-year, 10- to 30-year and 30- to 50-year all showing much higher volumes year-on-year, with £47 billion, £22 billion and £5 billion respectively.
So, not huge volumes, but good increases and encouraging growth in longer-dated swap tenors. That looks like a good first step, but is it evidence of the transition regulators are looking for?
Sterling swaps
To answer that we need to look at the volume of sterling Libor swaps for the same quarters.

Figure 3 shows:
- Good increases, comparing quarters in 2018 with a year earlier.
- The first quarter of 2018 with £2.6 trillion gross notional, up 60% from the first quarter of 2017.
- The second quarter of 2018 with £3.2 trillion gross notional, up 80% from the second quarter of 2017.
- Much more even distribution – relative to Sonia swaps – of gross notional by tenor, with the two- to five-year tenor the largest, generally followed by the five- to 10-year tenor.
So, no categorical evidence of a transition from sterling Libor to Sonia swaps; for that we would need to see flat or falling Libor swap volumes. But the respective rates of growth are very different, with Sonia swaps racking up over 200% growth, compared with 70% for Libor. That augurs well for Sonia’s future, but the tenor distribution shows the challenge ahead – it’s a long way from posting comparably meaningful volumes in tenors above two years.
Europe
The situation in Europe is very different. Declining Eonia volumes since the European Central Bank launched its large-scale asset purchase programme have resulted in the ECB working group recently selecting Ester – a brand-new rate – as the replacement for Eonia. For Euribor, the jury is out while reform efforts are underway.
Let’s take a look at euro swap volumes for both indexes to size the task ahead.
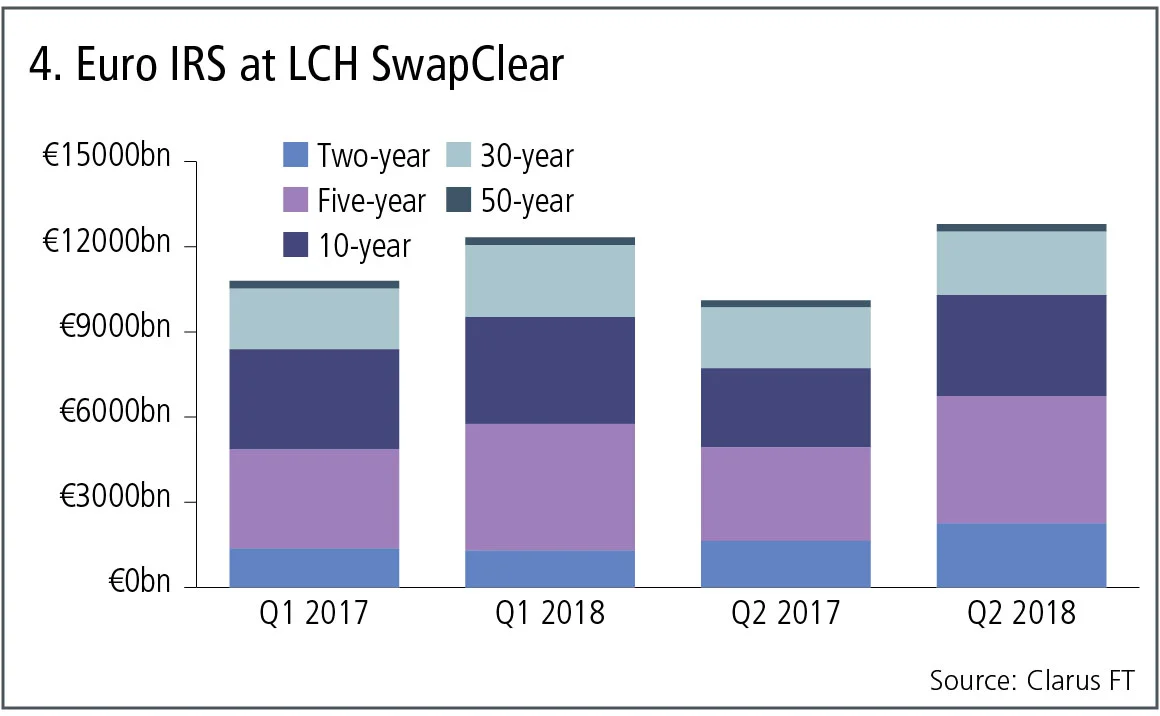
Figure 4 shows:
- Modest growth, comparing quarters in 2018 with a year earlier for Euribor swaps.
- The first quarter of 2018 with €12.3 trillion ($14.1 trillion) gross notional, up from €10.8 trillion in the first quarter of 2017.
- The second quarter of 2018 with €12.8 trillion gross notional, up from €10.1 trillion in the second quarter of 2017.
- The two- to five-year tenor is the largest, followed by the five- to 10-year tenor, with both the sub-two-year and 10- to 30-year tenor also showing massive volume.
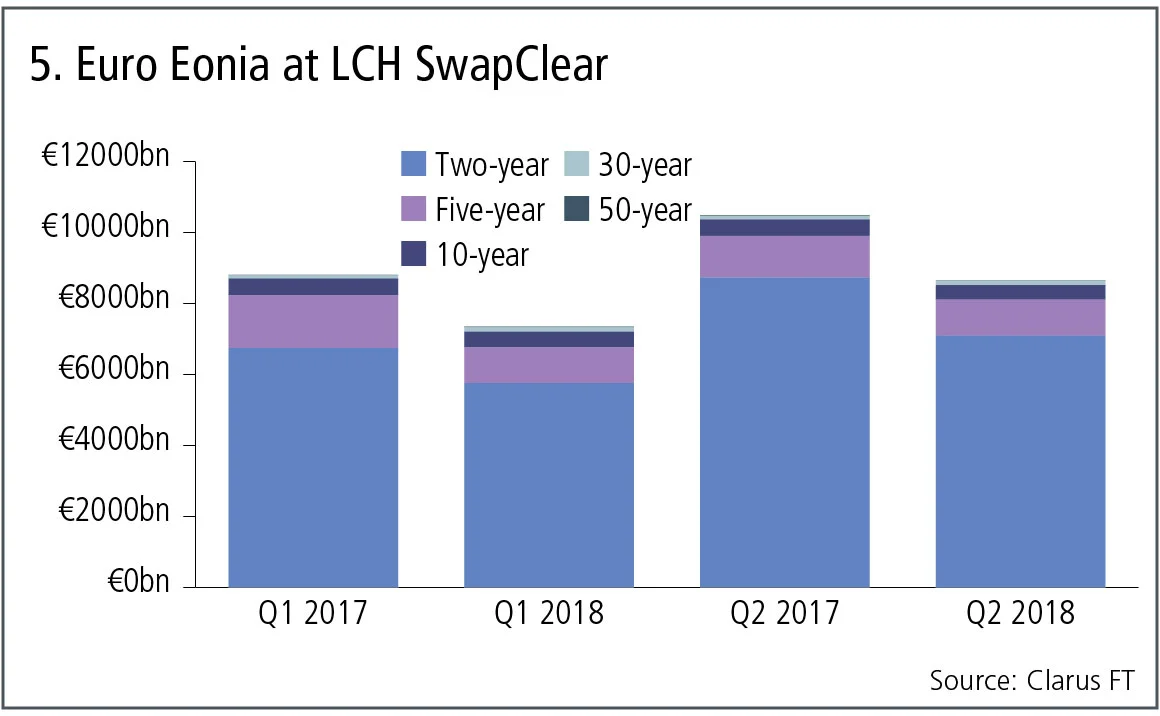
Figure 5 shows:
- Declines in Eonia volumes from a year earlier.
- The first quarter of 2018 with €7.3 trillion gross notional, down from €8.8 trillion in the first quarter of 2017.
- The second quarter of 2018 with €8.6 trillion gross notional, down from €10.5 trillion in the second quarter of 2017.
- While the sub-two-year tenor volumes dominate, there is substantial volume in the two- to five-year tenor and reasonable volume in the five-to 10-year tenor too.
Given the massive size of these volumes and the fact the ECB will only commit to publishing Ester by October 2019 – currently only a 10-day lagging pre-Ester is published – there is a lot of work to do. I’m not sure if the connotation here is more carrot or stick, probably equal measures of both are in order.
コンテンツを印刷またはコピーできるのは、有料の購読契約を結んでいるユーザー、または法人購読契約の一員であるユーザーのみです。
これらのオプションやその他の購読特典を利用するには、info@risk.net にお問い合わせいただくか、こちらの購読オプションをご覧ください: http://subscriptions.risk.net/subscribe
現在、このコンテンツを印刷することはできません。詳しくはinfo@risk.netまでお問い合わせください。
現在、このコンテンツをコピーすることはできません。詳しくはinfo@risk.netまでお問い合わせください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(ポイント2.4)に記載されているように、印刷は1部のみです。
追加の権利を購入したい場合は、info@risk.netまで電子メールでご連絡ください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
このコンテンツは、当社の記事ツールを使用して共有することができます。当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(第2.4項)に概説されているように、認定ユーザーは、個人的な使用のために資料のコピーを1部のみ作成することができます。また、2.5項の制限にも従わなければなりません。
追加権利の購入をご希望の場合は、info@risk.netまで電子メールでご連絡ください。
詳細はこちら コメント
オペリスク・データ:バイナンスの大規模ハッキングを受け、損失が急増
また、米国の銀行はAMLに関する新たな罰金の波に直面しており、トルコの銀行は労働市場を操作しています。データ提供:ORX News

予測市場は、制度的な信頼性テストに合格できるのか?
専門家によると、規制対象の企業は、利用を可能にするために、信頼性の高い事象判定手法と商品横断的な証拠金管理が必要だとのことです

信用リスクモデリングにおけるAIには、なぜハイブリッドのアプローチが最も適しているのか
AIはモデルが四半期報告書以上の情報を把握するのを支援していますが、CROによると、ガバナンスが完全な自動化を妨げているとのことです
ポッドキャスト:アリエ・シェーター氏とハリオム・タツァット氏によるAIの説明可能性に関する対談
バークレイズのクオンツたちが、メカニスティックな解釈可能性を用いたAIの監視手法について語ります
スイスフラン建てローンの損失は、EUの消費者金融業界にとっての灰色のサイである
mBankのCROであるマレク・ルシュティン氏は、ポーランドの銀行への影響が、法的リスクのモデリングにおける盲点を浮き彫りにし、それがより広範な影響を及ぼしていると述べています。

オペリスクデータ:EFG、20年にわたるマネーロンダリングで巨額の損失を被る
また、ディープフェイクによる音声クローンがインテサの部門を騙し、仮想通貨関連のハッキング事件が相次いでいます。データ提供:ORX News

ナビエ・ストークス方程式からキロ単位の論文まで:AIがクオンツ研究に与える影響
AIが大量の成果を生み出す中、金融業界では、その出所、信頼性、重要性を評価するための信頼できる手段が必要とされています
AIを正しい軌道に乗せ続けるには、継続的な検証が鍵となる
意思決定ごとの検証を行うことで、ユーザーがAIの判断を信頼できるようになります