
Correlation
Equally diversified or equally weighted?
New diversification measure enables construction of equally diversified portfolios
Vol decay and correlation flips: CFM’s take on the Covid crisis
Market bounce-back blindsided quant investment firm – and others
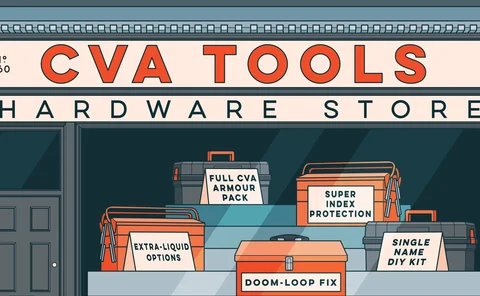
CVA desks arm themselves for the next crisis
March’s volatility forces dealers to fine-tune hedging strategies
SocGen mulls sale of structured product books after big losses
Rival Natixis also plans to place parts of its equity derivatives business in run-off mode

Spotting co-movement breakdowns with neural networks
Autoencoders can detect changes in relationship between assets in real time
Eigenportfolios of US equities for the exponential correlation model
In this paper, the eigendecomposition of a Toeplitz matrix populated by an exponential function in order to model empirical correlations of US equity returns is investigated.
Detecting changes in asset co-movement using autoencoders
ARR aims to anticipate volatility patterns to provide signals for risk management and trading
Bargain-hunting equity hedgers turn to FX
Currency options are cheap relative to stock index puts, but correlations are uncertain

Safe havens no longer safe, quants fear
Equity-debt correlation breakdown and negative bond yields make investors nervous
Dispersion trades suffer in coronavirus selloff
Losses put at roughly $150m – even before markets tanked on March 9
ICAAP/ILAAP – Unlocking business value from capital and liquidity assessment
Regulators consider banks’ internal capital adequacy and assessment process (ICAAP) and internal liquidity adequacy assessment process (ILAAP) important tools in managing risk. The European Central Bank’s (ECB’s) updated guidance – which came into effect…
An internal default risk model: simulation of default times and recovery rates within the new Fundamental Review of the Trading Book framework
This paper presents a new default risk model for market risk that is consistent with these requirements. The recovery rates follow a waterfall model that is based on a minimum entropy principle.
Ripping up the old asset class labels
Outmoded classifications of securities may be concealing market risk. AI has a better idea
Quant funds look to AI to master correlations
Machine learning shows promise in grouping assets better, predicting regime shifts
Will uncleared margin rules change the FX landscape?
As the next phases of uncleared margin rules come into force, there will be an economic driver for more clearing of FX. By Phil Hermon, Executive Director of FX Products at CME Group
The Fundamentals of market risk rules
With the 2022 Fundamental Review of the Trading Book (FRTB) deadline looming, banks are fast coming to grips with the amount of work still to be done to achieve a successful implementation
Engle: rise in geopolitical risks may be overestimated
Risk USA: Nobel laureate’s new ‘Geovol’ model suggests geopolitical risk no higher than during past 20 years
Politicians must heal a fractured UK society
Political journalist Robert Peston has grave concerns over the future of Britain, seeing profound risks with or without Brexit
Search for alpha in a volatile world
Alpha generation can be an elusive goal, particularly when trading volatility. Three different approaches to trading volatility were discussed by a panel looking at the role of systematic and carry strategies in finding profit in a high-volatility world

Study of correlation impact on credit default swap margin using a GARCH–DCC-copula framework
In this paper, the authors establish generalized autoregressive conditional heteroscedasticity–dynamic conditional correlation (GARCH–DCC) and constant conditional correlation (CCC) copula model frameworks to study time-varying correlation among credit…
Mirror-image factors are wiping out quant alpha
Equity momentum and value strategies are cancelling each other out, buy-siders say
Floating start date for 2020 stress test alarms EU banks
Regulator proposal could lead to less reliable market risk data, critics warn

On probability of default and its relation to observed default frequency and a common factor
This paper considers a definition of through-the-cycle as independent from an economic state that can result in a time-varying TTC probability of default.