Monthly credit data review: the Amazon effect and a rising Russian state
David Carruthers of Credit Benchmark looks at bank, sovereign and corporate credit risk data
As the world’s largest petro-state, at least by land area, Russia’s prosperity depends heavily on the behaviour of the energy markets. The sustained low prices of the 1990s brought a crippling depression; the oil boom of the 2000s led to a newly confident and aggressive Russia. The second piece of the picture is the sanctions imposed on Russian businesses, banks and individuals after the invasion of Ukraine in 2014. Though they remain in place and are set to be strengthened after the US Congress voted on renewed sanctions this month, the Russian financial sector has staged a modest recovery, with credit ratings for major Russian banks - mostly state-owned - and the Russian government itself rising gently, though still remaining below investment grade.
Energy may be part of the reason why. Though oil benchmark prices have not moved substantially over the last month, there has been a general increase in credit quality in the energy sector around the world, with upgrades outnumbering two to one - significantly better than the picture in other sectors, where the downward trend of the previous month continued.
This month we take a more detailed look at the Russian government and Russian banks, as well as retailers, asset management firms, and investment-grade gains and losses in the past 12 months.
Global credit industry trends
Figure 1 shows industry migration trends for the most recent published data, as well as the history for the past 12 months.
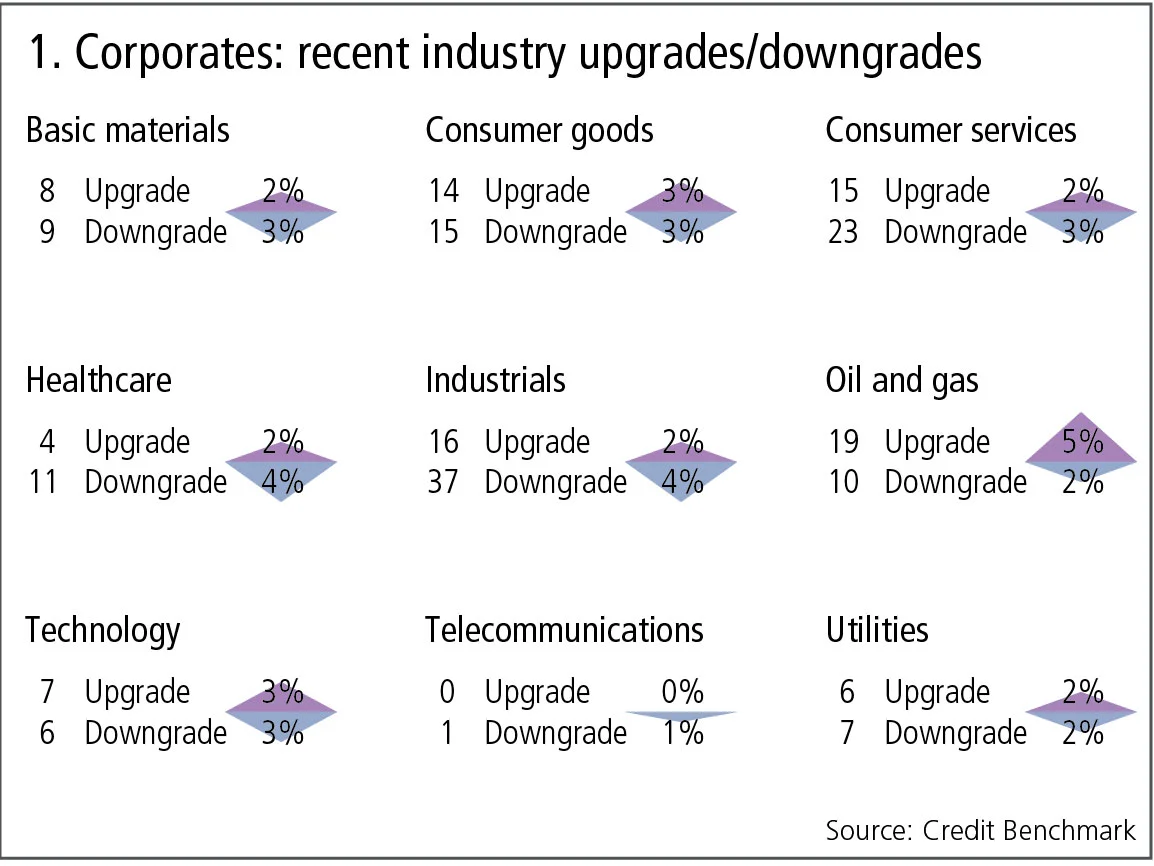
Figure 1 shows:
- Global corporate downgrades still outnumber upgrades by 1.3 to 1, but this is more balanced than last month when the ratio was 1.4 to 1.
- Industrials continue the pattern of last month, showing 37 downgrades against 16 upgrades. Last month, the equivalent figures were 39 downgrades against 35 upgrades, so the imbalance has increased.
- Consumer services and health care also show significant imbalances, with downgrades exceeding upgrades by a significant margin.
- Consumer goods have moved to a more balanced position following recent downgrades, and oil and gas upgrades outnumber downgrades by almost two to one.
Russia: sovereign risk and banks, comparison with global banks
The Russian economy has been severely hit by sanctions and weak oil prices, but recent data shows that the credit outlook is improving. Figure 2 plots the nine-month time series of credit trends for the government of Russia and 12 of the major Russian banks.
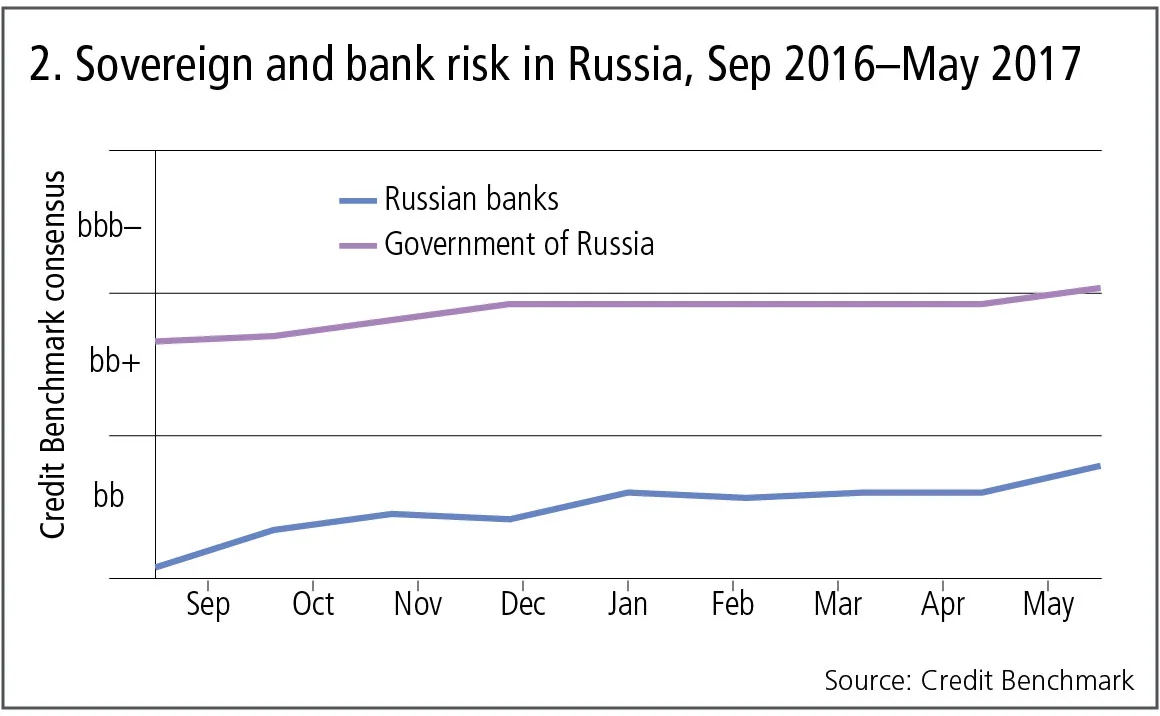
Figure 2 shows:
- The Russian government was viewed as bb+ in September 2016. It improved every month until the end of the year, but stabilised just below the investment-grade threshold. At the end of May, IRB banks moved the Russian government to investment grade (bbb–).
- The trend for the major Russian banks (mainly state-owned) is very similar, but they are still currently viewed as non-investment grade.
Credit trends in retailers
The traditional retail industry is suffering from the ‘Amazon effect’. But Amazon’s acquisitions of traditional retail businesses show that the impact of online competition can play out in a number of different ways. Figure 3 compares the credit trends for 46 US and 56 European apparel and general merchandise retailers as well as for Amazon and Whole Foods Market.
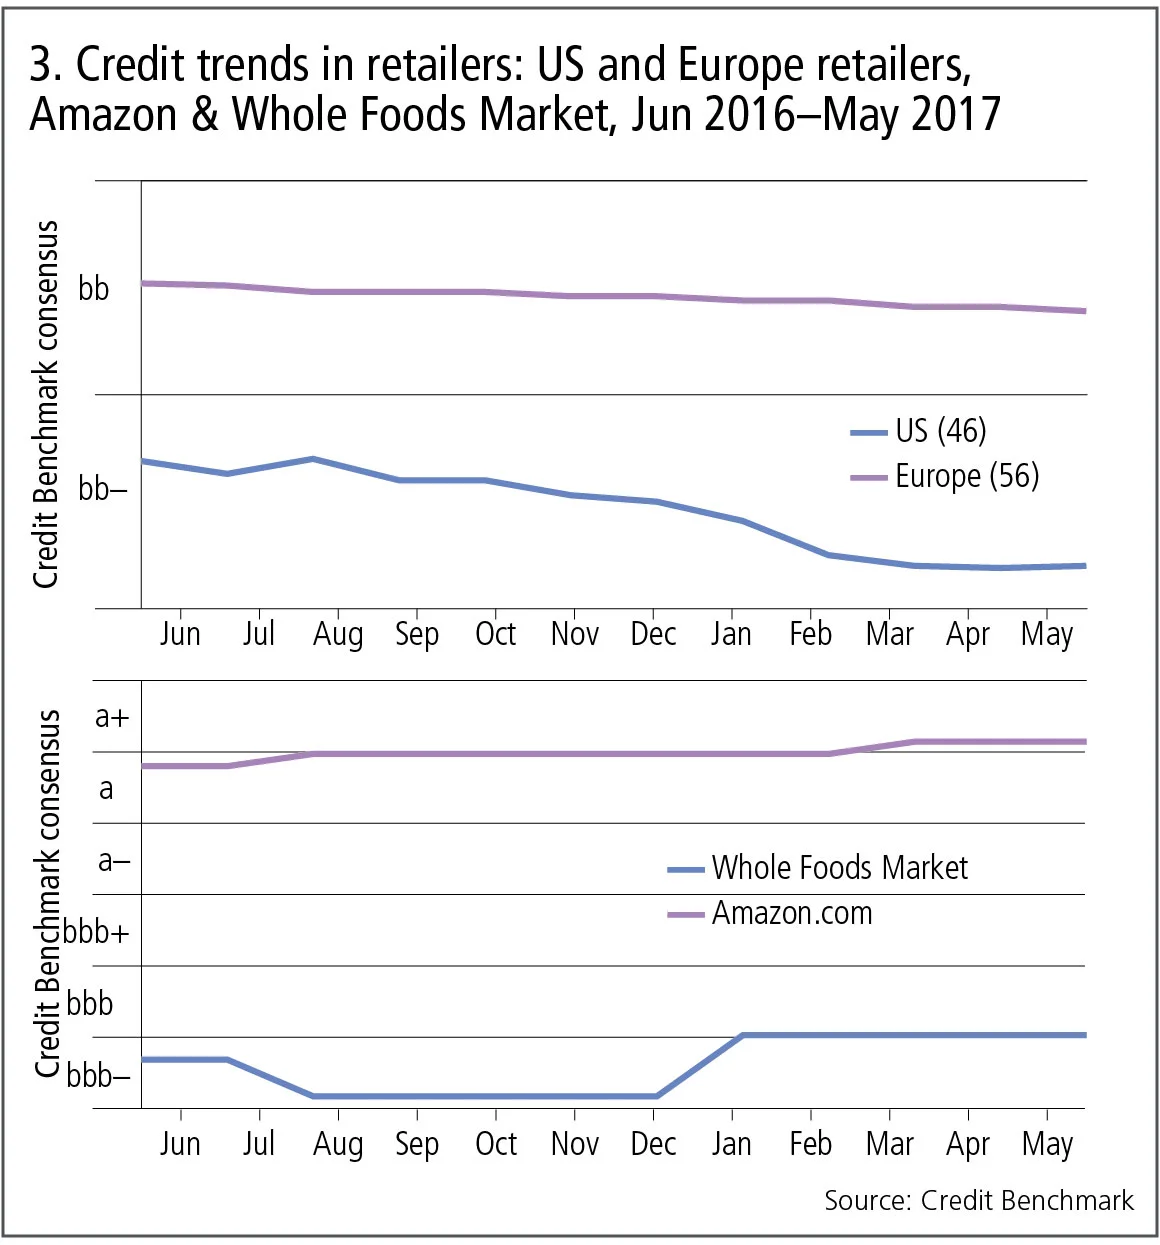
Figure 3 shows:
- Apparel and general retailers in both regions are already viewed as non-investment grade. The down trends have been the dominant pattern over the past 12 months. By comparison, the credit status of specialised retailers and food retailers has been stable or improving.
- The deterioration in the US is particularly noticeable; this may have implications for the future credit standing of European retailers as well.
- The credit consensus for Amazon has been steadily improving, and is significantly better than a typical corporate like Whole Foods Market.
Credit distribution of asset management firms
Asset management firms rarely feature in discussions of credit risk. Figure 4 shows the range for about 350 managers. These are a mix of traditional long-only managers, hedge fund managers and hybrid management firms.
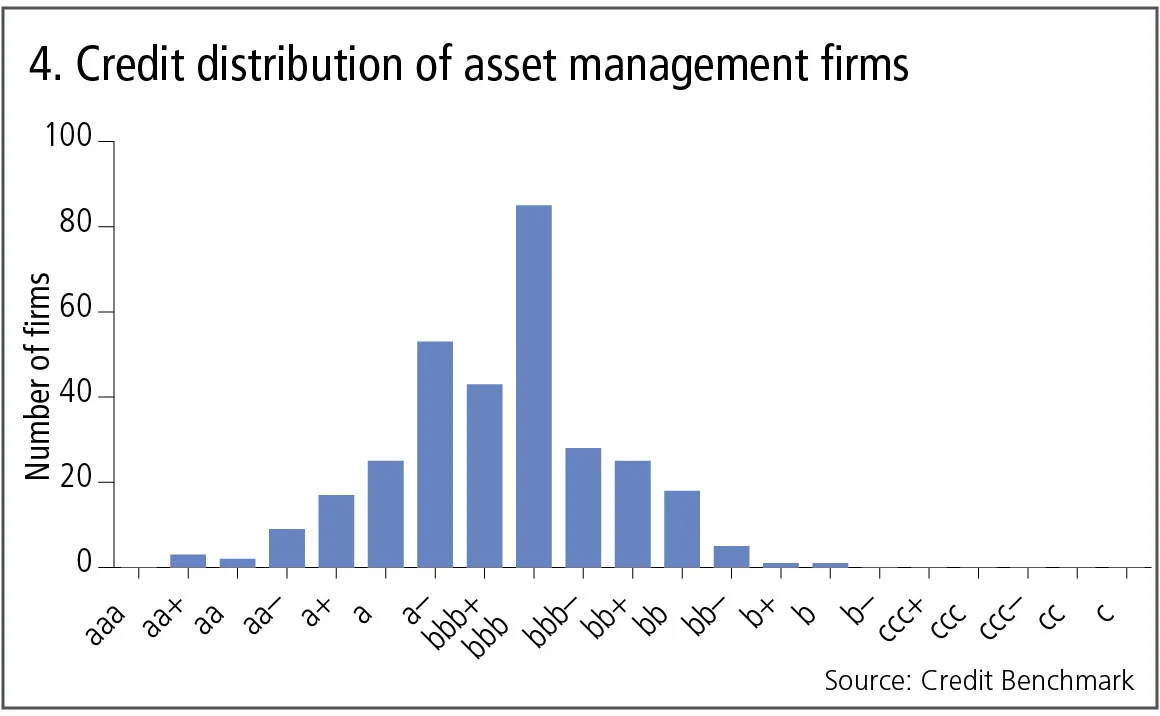
Figure 4 shows:
- Asset management companies show a surprisingly wide range of credit risks, from aa+ to b. The majority are viewed as bbb, with a large number just above this at a– and bbb+.
- This range probably reflects the size, longevity and performance of each firm, as well as the volatility and leverage of the assets that they manage. The distribution shown here indicates that the majority of firms represent a balance between these credit drivers, putting them in the same credit risk categories as a typical corporate.
- Firms in the right tail of the distribution may be excessively exposed to some of these risk sources.
Investment grade: gainers and losers in the past 12 months
The table in Figure 5 shows some of the major borrowers that moved into, or out of, investment grade in the past 12 months. The investment-grade threshold corresponds to an annual probability of default of 0.48%.
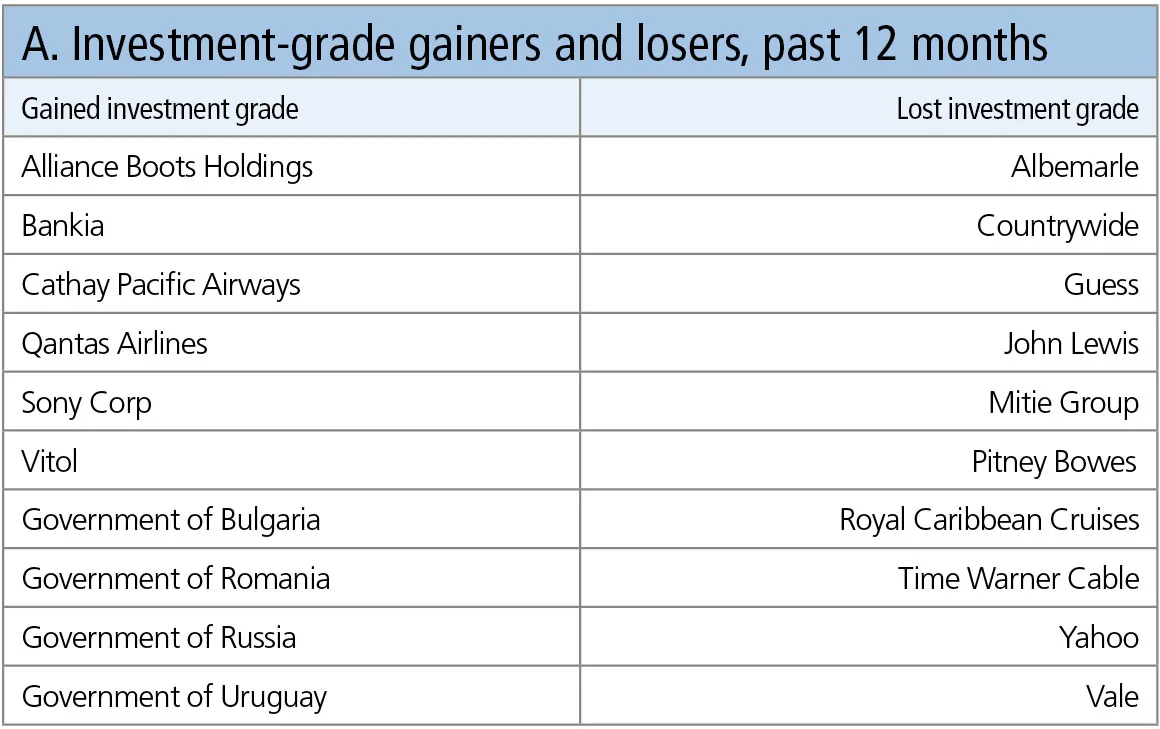
Table A shows:
- Four sovereigns have achieved investment grade, including the recent move in Russia’s status discussed above.
- Cathay Pacific, recently voted one of the top airlines in the world, was moved to investment grade, along with Qantas. Bankia’s move to investment grade reflects recent success across the European banking industry in strengthening balance sheets.
- The Amazon effect can be seen in the downgrades of John Lewis, Guess and Time Warner Cable.
- Some of the other downgrades – Albemarle, Yahoo, Countrywide, Mitie and Royal Caribbean – are more company-specific, but the underlying economic drivers are likely to affect similar companies in the same sectors.
David Carruthers is the head of research at Credit Benchmark, a credit risk data provider.
コンテンツを印刷またはコピーできるのは、有料の購読契約を結んでいるユーザー、または法人購読契約の一員であるユーザーのみです。
これらのオプションやその他の購読特典を利用するには、info@risk.net にお問い合わせいただくか、こちらの購読オプションをご覧ください: http://subscriptions.risk.net/subscribe
現在、このコンテンツを印刷することはできません。詳しくはinfo@risk.netまでお問い合わせください。
現在、このコンテンツをコピーすることはできません。詳しくはinfo@risk.netまでお問い合わせください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(ポイント2.4)に記載されているように、印刷は1部のみです。
追加の権利を購入したい場合は、info@risk.netまで電子メールでご連絡ください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
このコンテンツは、当社の記事ツールを使用して共有することができます。当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(第2.4項)に概説されているように、認定ユーザーは、個人的な使用のために資料のコピーを1部のみ作成することができます。また、2.5項の制限にも従わなければなりません。
追加権利の購入をご希望の場合は、info@risk.netまで電子メールでご連絡ください。
詳細はこちら コメント
信用リスクモデリングにおけるAIには、なぜハイブリッドのアプローチが最も適しているのか
AIはモデルが四半期報告書以上の情報を把握するのを支援していますが、CROによると、ガバナンスが完全な自動化を妨げているとのことです
ポッドキャスト:アリエ・シェーター氏とハリオム・タツァット氏によるAIの説明可能性に関する対談
バークレイズのクオンツたちが、メカニスティックな解釈可能性を用いたAIの監視手法について語ります
スイスフラン建てローンの損失は、EUの消費者金融業界にとっての灰色のサイである
mBankのCROであるマレク・ルシュティン氏は、ポーランドの銀行への影響が、法的リスクのモデリングにおける盲点を浮き彫りにし、それがより広範な影響を及ぼしていると述べています。

オペリスクデータ:EFG、20年にわたるマネーロンダリングで巨額の損失を被る
また、ディープフェイクによる音声クローンがインテサの部門を騙し、仮想通貨関連のハッキング事件が相次いでいます。データ提供:ORX News

ナビエ・ストークス方程式からキロ単位の論文まで:AIがクオンツ研究に与える影響
AIが大量の成果を生み出す中、金融業界では、その出所、信頼性、重要性を評価するための信頼できる手段が必要とされています
AIを正しい軌道に乗せ続けるには、継続的な検証が鍵となる
意思決定ごとの検証を行うことで、ユーザーがAIの判断を信頼できるようになります
AIがリスク管理の業務をうまくこなせるようになったら、どうなるのか?
リスク担当幹部であるアレックス・ゴルビン氏は、エージェント型AIが分析業務をますます担うようになる中、リスク分野で価値あるキャリアを築くにはどうすればよいかと問いかけます
変動の激しいエネルギー市場におけるインフレリスクの再評価
バークレイズのサミー・ベン・アウン氏は、インフレ・スワップのエネルギーショックに対する感応度をモデル化する手法について概説しています