
Risk measures
Estimation of risk measures for large credit portfolios
In this paper, saddle point techniques are used in the computation of risk measures for large mark-to-market credit portfolios with stochastic recovery and correlation between obligors depending on the state of the economy.
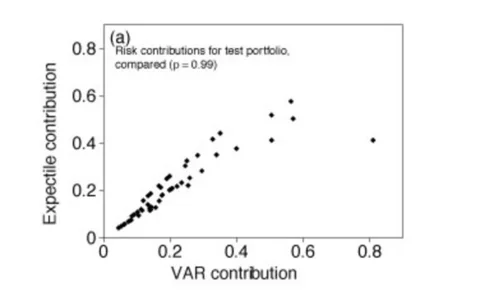
Expectiles behave as expected
Expectiles' results are analogous to those of value-at-risk and expected shortfall
JP Morgan’s ‘London whale’ losses spark VAR debate
In-house probe will look at role of internal model change, among other factors

Measures of predictive success for rating functions
Research Papers
An analytical framework for credit portfolio risk measures
An analytical framework for credit portfolio risk measures