
Risk management

European NSFR revamp could save banks billions in funding costs
Commission expected to ease pressure of liquidity ratio on derivatives positions when it unveils CRD V proposals

See the error of your VARs
Commonly-used VAR estimation method shown to underestimate risk

Adjusting VAR to correct sample volatility bias
David Frank proposes an adjustment to sample variance for the computation of value-at-risk

Compositional methods applied to capital allocation problems
In this paper, the authors examine the relationship between capital allocation problems and compositional data, and show that capital allocation principles can be interpreted as compositions.

Position vacant: unpicking energy’s hidden contract risks
Complex, long-term supply deals present job opportunity for risk managers

Risk Chartis Market Report: IFRS 9
Sponsored by Oracle, Moody's Analytics and AxiomSL
Decomposition of portfolio risk into independent factors using an inductive causal search algorithm
This paper presents a method to estimate and decompose a portfolio’s risk along independent factors.

Pension funds cautioned on equity-bond correlation
Buy-siders need to plug changes into VAR, say risk managers

US Bank’s op risk chief on terrorism and continuity
Jodi Richard explains overhaul of firm’s op risk programme, including crisis management plans

OCC’s Cunningham on why regulatory agencies need CROs too
The US banking supervisor has been taking a leaf out of banks’ books and putting the focus on enterprise risk management

Changing times mean a tougher job for op risk managers
Wave of organisational change at major banks heightens operational risk exposure

Intraday data does not improve daily VAR, research suggests
Bids to use bigger datasets give no better loss forecasts, says hedge fund

EBA stress test ‘obsolete’ after Brexit vote
Experts call for a rethink on setting scenarios for future tests

Futureproofing risk management
Sponsored Q&A: Numerix
Three lines of defence a struggle, say op risk heads
Separation "theoretically perfect" but "practically, hugely flawed" says UBS's Hunt

Static mitigation of volumetric risk
This paper formulates a functional optimization problem over a set of regular payoff functions to deal with the joint mitigation of combined price–volume risk using purely financial tools.

Investors must probe bank culture, says veteran financier
Ex-Barclays chairman says managers should take “stewardship responsibility” for bank conduct

Automated for the people
Sponsored survey analysis: Wolters Kluwer
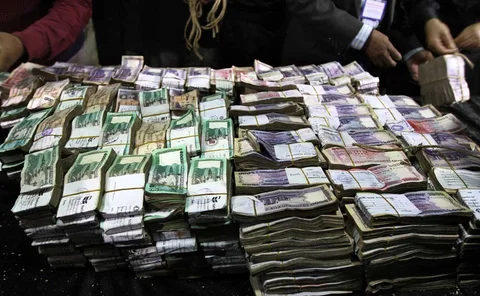
Bangladesh Bank theft shines light on cyber risk
Banks and regulators increasingly concerned amid high-profile cyber security breaches
Risk management and portfolio optimization for gas- and coal-fired power plants in Germany: a multivariate GARCH approach
This paper investigates the hedging effectiveness of energy derivatives traded at the EEX for the purpose of mitigating the risk exposure of gas- and coal-fired power plants in Germany.

People: SG Americas appoints chief culture and conduct officer
Nancy Harrington Jones is promoted; Cheri McGuire joins Standard Chartered as CISO; Penny Judd exits Nomura
Two sides of the same coin: risk measures in the energy markets
This paper investigates whether there are existing common model features that yield consistently superior results under both VaR and ES risk metrics in the energy commodities markets.
Stochastic receding horizon control for short-term risk management in foreign exchange
The authors of this paper formalize a methodology to manage short-term FX risk.
Evaluating the performance of the skewed distributions to forecast value-at-risk in the global financial crisis
This paper models the tail behavior of daily returns and forecasting VaR in order to evaluate the performance of several skewed and symmetric distributions.