
Risk management
Bank boards: goodbye to the prawn sandwich brigade?
Focus on personal liability makes risk committees a more effective challenge, say banks
FICC liquidity facility swells to $36 billion
Capped contingent liquidity facility adjusts in response to heightened liquidity risk
Data riches pose new test for risk managers
New quant tools must be balanced with old-fashioned intuition

Regulators zeroing in on non-financial risk, say banks
Several big financial firms said to be considering appointing heads of non-financial risk
Actionable data breach insights from op risk modelling
Thomas Lee, chief executive at VivoSecurity, and Martin Liljeblad, operational risk manager at MUFG Americas, examine how a data breach cost model can replace an advanced measurement approach in a structured scenario
No safety net for no-deal Brexit, warns BdE’s Alonso
UK banks should not rely on temporary rule waivers being granted in the event of a disorderly Brexit

Banks should quantify loan-loss model risk – academic
Models such as those used for IFRS 9, CECL or CCAR are prone to errors, and should be accounted for

BoE: UK banks falling short on stress-test model risk
Recent guidance on stress-test models could be expanded, says BoE exec

UK balancing market opening up to industrials
Will efforts to open UK balancing market garner interest beyond suppliers and aggregators?
Retail banking performance improves Groupe BPCE cost of risk
Retail banking network cost of risk falls 22bp to 15bp
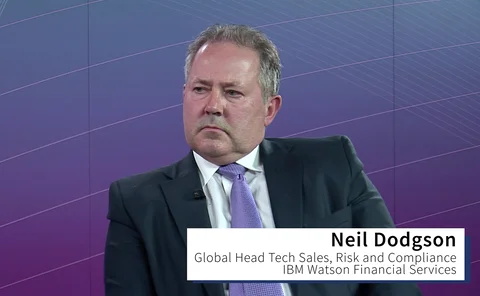
Risk management on course to move beyond cost centre
Video Q&A: Neil Dodgson, IBM Watson Financial Services

Credit default prediction using a support vector machine and a probabilistic neural network
In this study, the authors address the fact that the ranking of classifiers varies for different criteria with measures under different circumstances, by proposing the simultaneous application of support vector machine and probabilistic neural network …
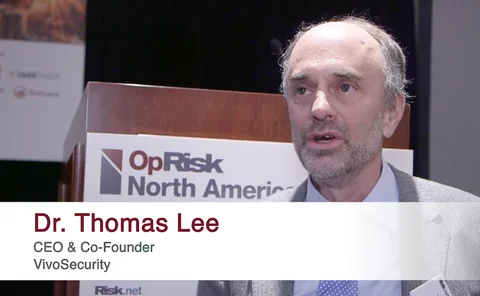
Sponsored video: Thomas Lee, Vivo Security
Thomas Lee, chief executive and co-founder of Vivo Security – a start-up firm based in Silicon Valley and sponsors at OpRisk North America – talks about how special the banking industry is to Vivo Security and why its approach to model risk management…

Maybank takes to the dark web to tackle hackers
Bank’s CRO and CTO discuss front-foot approach to cyber threats

Fed’s risk proposal puts banks on the defensive
New supervisory guidance will make business heads responsible for risk management

FRTB: ECB postpones model approval deadline
Postponement follows Basel’s decision to revise key elements of new market risk framework
Bridging networks, systems and controls frameworks for cybersecurity curriculums and standards development
This paper proposes a risk management framework designed to facilitate the alignment, integration and streamlining of professional practice standards and computer science/cybersecurity educational curriculums by bridging NPNATFs, SNIFs and RMCPFs.
Advancing on all fronts
Sompo Global Weather continues to expand its offering with timely, tailored weather risk solutions designed to service a growing global audience and diversification into new sectors supplying responsive solutions

Ensuring reliability in a rapidly changing energy landscape
Igor Koprivnikar, member of the management board at Gen-i, discusses what sets the organisation apart as the top power dealer in eastern Europe, the benefits that a global portfolio can bring for clients in regional European markets, and how strong…

Next-generation GRC
Webinar: Nasdaq BWise

European legislators to exempt CCPs from new bank rules
Support in Council and Parliament suggests leverage ratio, NSFR exemptions will be in final text

The quickest way to lose the money you cannot afford to lose: reverse stress testing with maximum entropy
This paper extends a technique devised by Saroka and Rebonato to “optimally” deform a yield curve in order to deal with a common and practically relevant class of optimization problems subject to linear constraints.
Optimal equity protection of Solvency II regulated portfolios
In the context of equity investments, this paper examines the relationship between the cost of acquiring protection (in the form of put option) and the reduction of capital charges that it entails. The paper develops the idea that Solvency II regulations…