
Model risk

Portfolio optimisation via replication
Filippo Della Casa and Michele Gaffo propose a new framework to run portfolio optimisation for life insurance business, by exporting the replicating portfolio technique from risk management to investment management. In particular, they develop a new risk…

Applied risk management series: Integrating stress tests with risk management
Stress testing is a vital part of successful risk management, but risk managers at energy trading firms frequently face obstacles in designing and implementing successful stress testing programmes. In this article, Carlos Blanco provides some advice on…

Risk managers too focused on model outputs, Lloyd’s risk head says
Risk managers need to look beyond models and consider a wider universe of risks, says Reeves
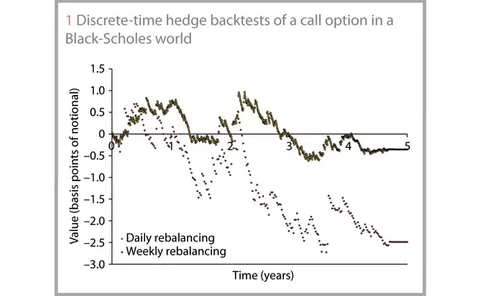
Hedge backtesting for model validation
Hedge backtesting for model validation

Quant Congress Europe: Test models as you build them, says BAML expert
With the 'London Whale' modelling failures still casting a shadow over the industry, BAML model risk head advocates ongoing testing
Copulas and credit models
Copulas and credit models

Non-linear mixture of asset return models
Non-linear mixture of asset return models

A model future (part I)
Models that use factors such as key risk indicators, or KRIs, for inputs align the op risk function with credit risk and market risk - and may increase the effectiveness of operational risk within an organisation. Marcelo Cruz looks at key factors in…

On humility
It's nice to see op risk managers becoming more aware of their limitations

Beware of data leverage
Beware of data leverage


OpRisk North America: Crisis highlighted op risk model failures, says Adachi
Model risk emerged as a key lesson from the crisis – and a significant variation in op risk modelling approaches exists today, says Sigor chair
Solvency II modelling could cause systemic risk, industry warns
Industry experts warn uniform modelling under Solvency II could lead to risk contagion
Bayesian lessons for payout structuring
Bayesian lessons for payout structuring
Data governance under the regulatory microscope
Consolidation process
Validating interest rate models under Solvency II
With Solvency II fast approaching, obtaining approval for your internal model is increasingly important. A key part of this process will be to demonstrate the ability of the model’s scenario generation to describe the evolution of interest rates…
Beyond distributional analysis
In the third article in a four-part series, David Rowe considers the need for financial risk management to move beyond distributional analysis to consider more qualitative inputs

It's NOT the econometrics, stupid
Risk modelling has come under the microscope since the onset of the crisis, with many blaming market risk models for exacerbating the crisis. Elizabeth Sheedy presents a defence of quantitative techniques
Tails of the unexpected
Credit Models

The top 10
OpRisk & Compliance outlines the top 10 challenges readers and their firms will face in 2008. By David Benyon, with additional reporting by Ellen Davis
A call to action
The global credit crunch shows just how much the world's financial services firms need to raise their game when it comes to risk management, says Charles Dallara, managing director of the Institute for International Finance. By Ellen Davis