
Santander
Barclays and Lloyds improve resilience to stress tests, HSBC falls back
Capital headroom above pass/fail thresholds increases to 250bp at lenders
IFRS 9 transition eases UK banks’ path through stress tests
Aggregate CET1 ratio 130bp lower without transitional relief
LCRs show US banks run more risk than European peers
The gap between the two averages has widened over the past three quarters to 250bp from 212bp
EU G-Sibs cut $14 billion in op risk
Banco Santander posted the largest decline – at 7% – with op RWAs falling to $70 billion
Santander loan-loss reserves eat into profits
Group-wide provisions pushed higher by the bank's US unit, which saw loan-loss reserves leap 44% to €649m over the quarter
Loan losses bedevil Lloyds in EU stress tests
UK bank saw largest CET1 decline due to asset impairment of EU-wide sample
European credit model outputs vary wildly
Risk densities range widely and out-of-sync with average probabilities of default
Corporate loan RWAs doubled by standardised approach
RWA densities for corporate loans under standardised approach stand at 94%, for A-IRB just 43%
Deutsche Bank's risky corporate loan pile towers over peers
German lender has one-quarter of all high-risk corporate loans reported by EU big banks

SRB should publish banks’ MREL requirements, says Enria
But market abuse rules need amending to avoid SRB disclosing confidential resolution actions
Standardised market RWAs on the rise at EU banks
Standardised approach-generated RWAs increase €4.7 billion across 12 banks
EU bank leverage increases in H1
Average leverage ratios degrade 19 basis points in six months to June

EU infighting blocks Basel recognition of banking union
Treating eurozone as single jurisdiction could slash G-Sib capital, but the 19 member nations have differences to settle first
Fed stress tests: foreign banks lag US on capital estimates
On average, IHCs missed the Fed’s estimates of the amount their CET1 ratios would fall in the 2018 test cycle by 213bp, compared with 109bp by US lenders
Santander shakes off toxic loans
NPL ratio 145bp lower than at time of Banco Popular takeover
EU banks get different MREL levels and deadlines
Average bail-in requirement is 28% of RWAs
People moves: SocGen hires new strategy head, RBS loses CFO, and more
Latest job changes across the industry
Ring-fencing to starve investment banks of deposit funding
BoE data estimates non-ring-fenced banks will have access to just 4% of household deposits
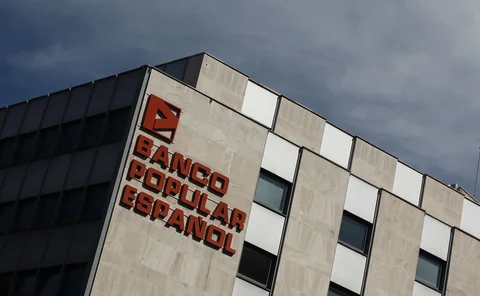
SRB denies conflict of interest claim on Banco Popular
Bondholders poised to challenge “no creditor worse off” valuation if compensation is denied
European banks op risk losses dominated by business failures
Losses relating to accident and neglect account for 38% of op risk losses at eight big dealers
Take-up of credit modelling varies at European banks
Percentage of credit RWAs calculated using IRB approaches ranges from 42% to 91% across large dealers
Fraud makes up bulk of UK bank op risk loss events
Internal and external fraud on average equalled 64% of all op risk events in 2017 across four large dealers

Regulators zeroing in on non-financial risk, say banks
Several big financial firms said to be considering appointing heads of non-financial risk
The special one: a eurozone G-Sib waiver for BNP Paribas
Experts say French bank’s G-Sib buffer could fall to 1%, saving €3 billion in regulatory capital