
Foreign exchange
Markit continues acquisition spree
Markit has acquired Netherlands-based MarketXS, a provider of software and technology for data distribution and trading solutions to the financial services industry.
The traders' tool box
traders' corner
Shock news: Structured products are good for you
Market view
Managing the mortgage maze
Uk Mortgages

Hot property
Derivatives

Reinventing the fund
Funds of Hedge Funds

Bulking up
Annuities

A successor to VAR?
Strees Testing
Delta hedging the load-serving deal
In this article Andrew Klingler takes a closer look at the residual risk when a load-serving contract is hedged with forwards. The residual risk components are described quantitatively and a formula for the minimum variance hedge is outlined
Amine Bel Hadj Soulami
Amine Bel Hadj Soulami talks to Stella Farrington about his rise to global head of commodity derivatives at BNP Paribas
Kick-start for coal futures
Ice Futures and the European Energy Exchange have gone head-to-head in the latest attempt to kick-start coal derivatives trading. Oliver Holtaway investigates
Vultures in Congo
Energy companies have long accepted a degree of country risk when investing in developing nations. But oil and gas companies now face a new threat to their international investments - and its origins lie closer to home. Andrew Derman, Andrew Melsheimer…
Bright forecast for weather derivatives
To attract more corporate end-users, purveyors of weather derivatives are creating new products in search of the perfect hedge, as Catherine Lacoursiere finds

L Sankar, Jure Skarabot
Citigroup credit derivatives specialists explain why the Gaussian copula model, despite its flaws, is still the market standard for analysing correlation
Paying a premium for bank analysts
Bank analysts are paid more than other credit analysts; but are they really worth it? Toby Nangle did the number-crunching to find out
Credit derivatives: the next generation
Now that credit default swaps and other credit derivatives are moving into the mainstream of financial trading, a new range of products and structures are being developed using synthetic techniques. Calyon's Loic Fery and Ally Chow review some of these…
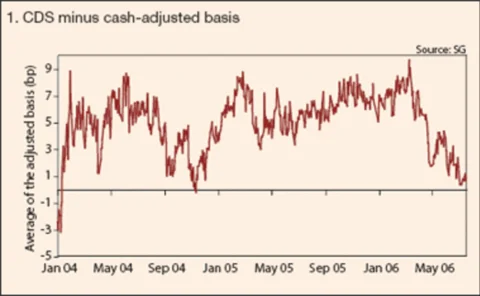
Cash-CDS basis
Market graphic
