
Implied volatility
Yen exotics re-hedging fuelled vol surge, say traders
USD/JPY spike forced dealer stampede into call options, pushing FX vol even higher

Estimating value-at-risk using quantile regression and implied volatilities
In this paper the authors propose a semi-parametric, parsimonious value-at-risk forecasting model based on quantile regression and readily available market prices of option contracts from the over-the-counter foreign exchange interbank market.
Traders turn to ruble NDFs to avoid sanctions trouble
Basis between physical and non-deliverable trades hits record high as users shun local currency
Rough volatility moves to exotic frontiers
New simulation scheme clears the way for broader application of the rough Heston model
Efficient simulation of affine forward variance models
Andersen's quadratic-exponential scheme is used for simulations of rough volatility models
What quant finance can learn from a 240-year-old problem
Optimal transport theory offers a data-driven way to calibrate derivatives pricing models
Forecasting volatility and market returns using the CBOE Volatility Index and its options
This paper examines the CBOE VIX, the VIX options’ implied volatility and the smirks associated with these options.
Follow the moneyness
Barclays quants extend Bergomi’s skew stickiness ratio to all strikes
Using equity, index and commodity options to obtain forward-looking measures of equity and commodity betas and idiosyncratic variance
This paper presents a means to extract forward-looking measures of equity and commodity betas, and idiosyncratic variance.

FX option selling and weak demand behind vol slide, say traders
EUR/USD vol inches towards pre-Covid lows, but some believe inflation could upset trend
OCC quants tout anti-procyclical margin method
Technique aims to lower initial margin calls in times of stress without sacrificing risk sensitivity
An approximate solution for options market-making
An algorithm for the market-making of options on different underlyings is proposed
Goldman inks modelling, data tie-up with MSCI
Move to cross-sell risk analytics could herald further content deals for bank’s Marquee platform, says sales chief

Is short vol taking the long count?
Short volatility players try to box clever after strategy’s Covid rout
Modeling realized volatility with implied volatility for the EUR/GBP exchange rate
This paper concerns the application of implied volatility in modeling realized volatility in the daily, weekly and monthly horizon using high-frequency data for the EUR/GBP exchange rate.
Rough volatility’s steampunk vision of future finance
Some of the trickiest puzzles in finance could be solved by blending old and new technologies
The volatility paradigm that’s stirring up options pricing
‘Rough volatility’ models promise better pricing and hedging of options. But will they catch on?

Nowcasting networks
The authors devise a neural network-based compression/completion methodology for financial nowcasting.

SABR smiles for RFR caplets
The SABR model for volatility is adapted to price risk-free rate caplets
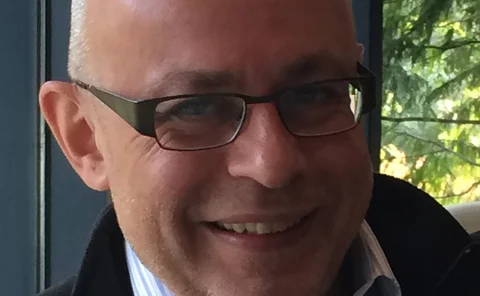
Quants of the year – Jim Gatheral and Mathieu Rosenbaum
Risk Awards 2021: Rough volatility models could make the options market more efficient
Numerical techniques for the Heston collocated volatility model
In this paper, the authors discuss all aspects of derivative pricing under the Heston–CLV model: calibration with an efficient Fourier method; a Monte Carlo simulation with second-order convergence; and accurate partial differential equation pricing…

Markets search for FX factor as rates fall flat
Traders signal shift to currency strategies, but is it passing fad or permanent fixture?
Strike a pose: deal contingents back in vogue after mid-year slump
M&A revival breathes life into deal contingent trades, but elevated risk keeps prices high
FX volatilities fall on receding US election fears
Polls point to a decisive Biden win – though some worry market is being complacent