
Stress-testing
Vol decay and correlation flips: CFM’s take on the Covid crisis
Market bounce-back blindsided quant investment firm – and others

Covid-19 tumult prompts rethink of buy-side risk management
Buy-side risk survey: investment firms making changes to their risk reports, stress tests and concentration limits
Inside the Fed’s secret liquidity stress tests
Lobbyists and Quarles train sights on horizontal exams that can shape bank risk appetite
Stress testing, home working and the move to €STR
The week on Risk.net, August 8–14, 2020
How UBS AM dealt with Covid-19 crunch
Buy-side risk survey: Swiss giant had planned for liquidity squeeze, says CRO – but not one like March
Internal stress tests of EU banks not up to scratch – ECB
Only one in 10 banks’ internal tests are tougher than supervisor-run programmes

Funds turn to stress-testing in fast-forward and reverse
Buy-side risk survey: Covid-19 is changing the way investors think about stress tests
AllianceBernstein’s CRO on managing risk with imagination
Buy-side risk survey: Andrew Chin suggests ripping up old assumptions and creating crisis ‘playbooks’

Fed’s approach to stressing op risk frustrates banks
Regulator’s stress test results overshoot banks’ numbers, threatening capital plans

Benchmarking operational risk stress testing models
This paper outlines several approaches to benchmarking operational loss projections under stressed scenarios using both accounting metrics and historical loss experience.

Mariner’s CRO on avoiding predictable surprises
Buy-side risk survey: relative value specialist builds shocks into investment strategy
Coronavirus shock to hit diversified lenders hardest – ECB
Diversified and wholesale lenders projected to see CET1 ratio decline 7 percentage points under worst-case scenario
Severe Covid recession could topple some EU banks
One-quarter of lenders would see CET1 ratios fall below 6.8%
Pimco’s Mariappa on iterating through the Covid-19 crisis
Buy-side risk survey: bond giant’s risk head is paying closer attention to idiosyncratic risks

Before and after the Covid-19 storm: buy-side risk survey
Wide-ranging survey reveals what worked and what didn’t in March – and what will change as a result
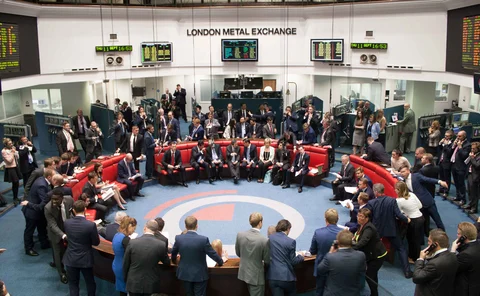
LME distressed at severity of Esma stress tests
Watchdog’s simulated price shocks said to be unprecedented in metals markets
BNY Mellon strengthens capital stack
CET1 capital increased 9% quarter-on-quarter

Concerns roil prop clearing waters in wake of ABN losses
State-backed lender insists few clients have defected – but sharks circle, post-Parplus
At top US banks, stress test capital hit driven by dividends
Shareholder giveaways make up bulk of post-stress capital losses at JP Morgan, Morgan Stanley, Bank of America
US banks want urgent guidance on capital plan updates
Call for Fed to provide Covid scenarios by start of September, not in fourth quarter
How the Fed’s Covid stress test got stuck in the middle
Experts fear CCAR add-on has neither informed investors nor guided capital management
Foreign banks and Fed at odds on stress test impacts
HSBC North America predicted a loan-loss rate of 2.7%, well below the Fed’s 6% estimate

Banks eye post-pandemic shake-up of op risk scenarios
Firms seek better handle on impact of global shocks, and hope to avert regulatory attention
Three systemic US banks face stress capital buffer add-ons
JP Morgan, Goldman Sachs, Morgan Stanley will see minimum requirements increase under new regime