

Podcast: Blanka Horvath and Gordon Lee on market generator models
Quants explain the application of the latest techniques
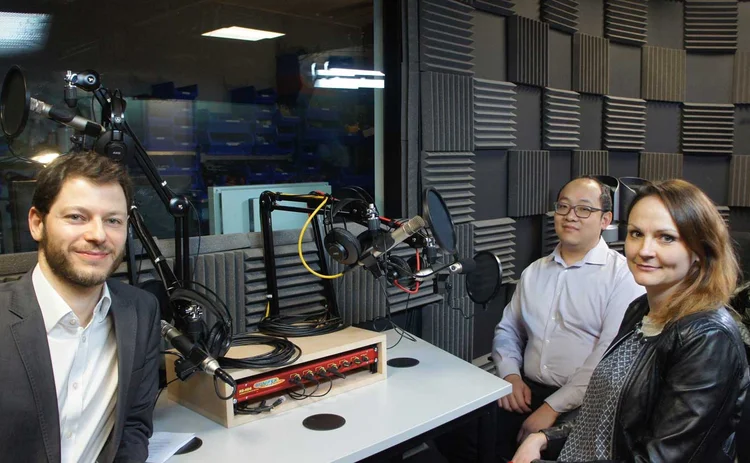
In this Quantcast episode, we talk with Blanka Horvath, finance lecturer at King’s College London and co-winner of Risk.net’s ‘Rising star in quant finance’ award, and Gordon Lee, executive director with the quantitative analytics group at UBS.
The conversation focuses on Horvath and Lee's involvement in the development of generator models in finance.
A generator model is a neural network-based technique used to produce a synthetic dataset that closely resembles the statistical properties and dependence structures of the original dataset.
Our discussion follows a previous Quantcast, in which Alexei Kondratyev and Christian Schwarz explained how a restricted Bolzman machine works and what it can be used for.
Horvath has been working on a class of market generators that use ‘variational auto-encoders’ to encode the information contained in a data sample in only a few parameters, and then use those parameters to create new datasets with the same properties as the original.
In a joint work with Hans Buehler, Oxford University's Terry Lyons, Imanol Perez Arribas and Ben Wood, Horvath developed the variational auto-encoder method, and created a version of it that can work with a very low number of data samples. It is able to produce paths, such as price paths, in a way that is consistent with the structure of the time series. The authors used the theory of signatures – a concept introduced by Lyons.
While the formal definition of signatures is rather technical, Lee offers here a simple explanation of how they operate and explains why this generator model is relevant to the calculation of data-intensive quantities such as that of valuation adjustments.
Horvath adds that they are a versatile and very quick to compute. “Signatures are an extremely powerful way of encoding the features of the path” she says, adding, “They capture the most important components of the path, and if you take more and more it will converge to the original.”
The practicality of this research project was clear from the beginning. “We started looking into producing artificial data that we could feed into the deep hedging engine,” explains Horvath, referring to the data-driven methodology developed by Buehler and his co-authors to obtain a hedging strategy without using the classic Black-Scholes formula.
With regards to this particular application, the introduction of generator models allows the user to overcome issues related to datasets having a short history, which is typical of most financial time series. Twenty years of daily prices produce only about 5,000 data points, while the training of the reinforcement-learning algorithm of deep hedging requires many more.
Index
00:00 Intro
02:15 Blanka and Gordon introduce the market generators
05:12 What market generators are suitable for finance?
09:44 What are variational auto-encoders?
16:00 An explanation of the concept of signatures
22:35 Application of signatures
28:00 Application of variational auto-encoders
30:00 Will data-driven models replace the classic models?
33:30 Next steps in research
To hear the full interview, listen in the player above, or download. Future podcasts in our Quantcast series will be uploaded to Risk.net. You can also visit the main page here to access all tracks, or go to the iTunes store or Google Podcasts to listen and subscribe.
コンテンツを印刷またはコピーできるのは、有料の購読契約を結んでいるユーザー、または法人購読契約の一員であるユーザーのみです。
これらのオプションやその他の購読特典を利用するには、info@risk.net にお問い合わせいただくか、こちらの購読オプションをご覧ください: http://subscriptions.risk.net/subscribe
現在、このコンテンツを印刷することはできません。詳しくはinfo@risk.netまでお問い合わせください。
現在、このコンテンツをコピーすることはできません。詳しくはinfo@risk.netまでお問い合わせください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(ポイント2.4)に記載されているように、印刷は1部のみです。
追加の権利を購入したい場合は、info@risk.netまで電子メールでご連絡ください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
このコンテンツは、当社の記事ツールを使用して共有することができます。当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(第2.4項)に概説されているように、認定ユーザーは、個人的な使用のために資料のコピーを1部のみ作成することができます。また、2.5項の制限にも従わなければなりません。
追加権利の購入をご希望の場合は、info@risk.netまで電子メールでご連絡ください。
詳細はこちら カッティング・エッジ
ポッドキャスト:アリエ・シェーター氏とハリオム・タツァット氏によるAIの説明可能性に関する対談
バークレイズのクオンツたちが、メカニスティックな解釈可能性を用いたAIの監視手法について語ります
ブラックボックスの先へ:金融分野におけるLLMの解釈可能性
メカニズムに基づく解釈可能性、そして計算メカニズムにおける変更点を特定
P・Qキャリブレーションと経路依存的な変動性の整合
校正の堅牢性を向上させることを目的とした混合アプローチを提案します
ポッドキャスト:アレクサンダー・バルジキン氏によるFXマーケットメイキングのモデリングについて
HSBCのクオンツが、逆選択、価格の読み取り、および内部流動性管理について論じます
逆選抜と価格観測下における最適な価格提示
現実世界における重要な影響を考慮するために、マーケットメイキング・モデルが導入されています。
ポッドキャスト:バーネット氏とピアウ氏が語る、XVAに関する包括的なフレームワーク
バークレイズのクオンツ担当者が、長年の課題に対する同行のアプローチについて解説します
価格調整の基本的な表現
デリバティブ価格調整の統一的な表現について提示します

混合モデルフレームワークにおけるテールの調整
ファットテール特性を再現するために、ガウス分布とスチューデントのt分布を組み合わせたデータ生成器をご紹介します
