
Default risk

Bailout obsession holds back US CCP resolution regime
Dodd-Frank leaves legal uncertainty, but proposed alternatives could be even worse

Portfolio credit risk model with extremal dependence of defaults and random recovery
This paper proposes a portfolio credit risk model with random recovery rates.

Goodness-of-fit for discrete-choice models of borrower default
This paper demonstrates that the rank-order tests are unreliable for assessing models to be used to predict probabilities.

Default risk charge: modeling framework for the “Basel” risk measure
This paper presents a comprehensive model framework for DRC that is compliant with the revised Basel regulatory framework.
Banks voice fresh concerns over CCP non-default losses
Dealers could face cash calls to recapitalise an ailing CCP that suffers a critical non-default loss under FSB proposals
Default risk of money-market fund portfolios
This paper proposes a semi-analytic approach to quantify the default risk associated with Money-Market Fund (MMF) portfolios.

Cutting Edge introduction: systematic systematic factor models
Credit factor models tend to obscure the economics in favour of tractability – and this puts them at odds with rigorous arbitrage-free martingale pricing methods. To resolve this, quants are looking more closely at what a systematic risk factor actually…
Isda AGM: CCP ‘Armageddon’ could lead to sovereign default, warns HSBC exec
Single bank default could affect multiple CCPs, leading to crippling default contribution for existing members and a chain of bank failures

The impossibility of DVA replication
The impossibility of DVA replication

Spanish banks allowed to ignore default risk for sovereign bonds
Banco de España is one of a number of European supervisors allowing its banks to ignore a Basel 2.5 requirement to model default risk on government bonds
Risk Annual Summit: Bank deleveraging 'might not be cyclical'
Aircraft, shipping and project finance all set to lose out as banks seek to constrain capital consumption, panellists warn
Variable selection in default risk models
Research Papers

US distressed debt funds look to euro crisis for opportunities
Stressful situations

Planning for bankruptcy of a major counterparty
Backup plan
HKEx moves to introduce margins for cash clearing members
HKEx plans to beef up its risk management following the bankruptcy of Lehman Brothers in September 2008 by introducing margin rules and seeking more funds from cash clearing members. The move would bring cash clearing more in line with existing…
Defaults by stealth are rare: Marty Fridson column
Defaults by stealth are rare

The limitations of using correlation in default prediction
Market analysis: Correlation and default
'An explosion of sovereign debt'
'An explosion of sovereign debt'

LBOs remain vulnerable to restructuring, says Pimco’s Jessop
The current low default rate in the high yield market does not tell the full story, the executive vice-president and portfolio manager at Pimco tells Credit.
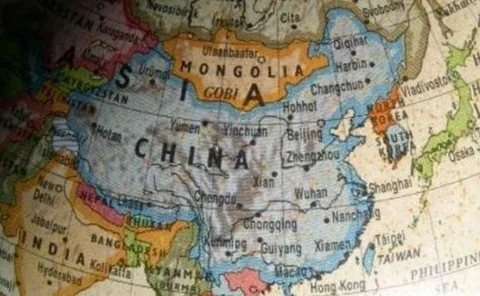
China's bond laws remain a 'quagmire' for foreign investors, warns advisory firm
Investors in Chinese corporate bonds may struggle to recover their money in the event of a bankruptcy, according to FS Asia Advisory.

Execs would not be surpised if Eurozone shrinks, report claims
RBC Capital Markets survey say Greece most likely country to leave the eurozone.