

Full stream ahead for bonds
Price streaming offers cost savings and operational efficiencies, but it could fragment liquidity
In a sign of just how technology is changing trading, some of the largest dealers are bringing the Netflix model to corporate bonds.
At least six major dealers – Bank of America, Barclays, Citi, Goldman Sachs, JP Morgan and Morgan Stanley – have started streaming live, executable prices directly to select clients.
These initiatives are still in their infancy and details are sparse. Dealers are wary of divulging how many clients they have signed up, or even the number of bonds for which streaming prices are available. Even so, one banker says the bond market may be on the cusp of a “seismic shift”.
Change is long overdue for what has traditionally been a staid and hidebound corner of the financial markets. While other asset classes, equities for example, are traded at the touch of a button – or algorithmically, without any human intervention – the majority of corporate bonds are still traded by phone.
Asset managers, under pressure to cut costs and improve efficiency, are receptive to new, electronic trading models. Streaming offers customised prices for each client and the ability to auto-execute a trade at any time.
In some ways, this mirrors the revolution that has swept through the home entertainment industry. Internet-streamed television and movie services, such as Netflix, Amazon Prime and YouTube, disrupted the incumbent terrestrial networks by putting consumers in control of the viewing schedule.
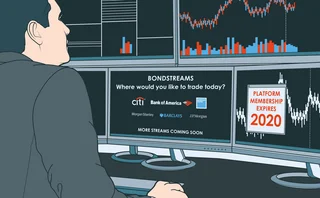
But with choice comes fragmentation and cost-creep. The growth in the number of streaming media services, each with their own subscription fees – not to mention the need for faster internet and smart devices – means committed viewers can easily end up paying more than for the old cable and satellite TV packages.
The shift to price streaming for corporate bonds could result in a similar dynamic. To handle the new feeds of bond prices, asset managers will need new tech – either developed in-house or bought off-the-shelf. The next generation of execution management systems will need to cope with an ever-expanding number of bilateral, dealer-to-client streams.
Streaming providers are likely to become more widespread. In addition to the major dealers, Tradeweb and MarketAxess offer streaming prices for corporate bonds. Non-bank liquidity providers may look to muscle in, as they have in other markets. Some forward-thinking asset managers already see the need for an aggregation service to bring efficiency to this new market.
“Think of it like a US interstate highway,” says one investor. “If there was a utility out there that would serve as the connections from the sell side to the buy side and back, so people could just jump on to those pipes, that would be better than dealers having to maintain hundreds of different connections.”
The danger is that price streaming, having started out as a clean, low-cost trading concept, ends up fragmenting liquidity and hiking costs. Television streaming has given consumers more programmes to watch, but finding them is harder and more expensive. Bond streaming must avoid the same fate.
But then, no-one wants to go back to the days of scheduled programming.
コンテンツを印刷またはコピーできるのは、有料の購読契約を結んでいるユーザー、または法人購読契約の一員であるユーザーのみです。
これらのオプションやその他の購読特典を利用するには、info@risk.net にお問い合わせいただくか、こちらの購読オプションをご覧ください: http://subscriptions.risk.net/subscribe
現在、このコンテンツを印刷することはできません。詳しくはinfo@risk.netまでお問い合わせください。
現在、このコンテンツをコピーすることはできません。詳しくはinfo@risk.netまでお問い合わせください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(ポイント2.4)に記載されているように、印刷は1部のみです。
追加の権利を購入したい場合は、info@risk.netまで電子メールでご連絡ください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
このコンテンツは、当社の記事ツールを使用して共有することができます。当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(第2.4項)に概説されているように、認定ユーザーは、個人的な使用のために資料のコピーを1部のみ作成することができます。また、2.5項の制限にも従わなければなりません。
追加権利の購入をご希望の場合は、info@risk.netまで電子メールでご連絡ください。
詳細はこちら 我々の見解
銀行システムを「換気」する時期が来たのか?
監視団体は基準の引き下げを懸念していますが、政策立案者は成長に注目しており、彼らは難しいジレンマに直面しています。

なぜ破綻処理計画を骨抜きにするのは良くないのか
銀行の破綻は避けられないものですが、銀行危機はそうではありません
日本の「大還流」?急速なリパトリは期待できない
GPIFによる米国債から日本国債への切り替えは段階的に行われる見通しであり、これはヘッジファンドにとってさらなる悪材料となる可能性があります
AIエージェントが、信頼できないスタッフのような存在である理由
GenAIシステムに内在する不確実性により、リスク管理担当者はより対立的なアプローチをとらざるを得ません

批判派は、パーペチュアルはすべてフロスだと言っています。しかし、数字はそうではないことを示唆している
TradFiを原資産とする永久先物に対する堅調な未決済建玉は、CMEやEurexといった既存の取引所にとって脅威となる可能性があります
SpaceXがCMEの個別銘柄先物に待望の追い風をもたらした
S&P 500先物契約へのIPO関連の追加契約として、新たな契約が急増する可能性があります
Bank vs non-bank: FX’s two-tier reality
CME and LSEG data show banks provide sticky and broad liquidity, while non-banks cling tightly to the price
規制当局はエンフォースメントを甘くしているのか?(そして、私たちはそれを気にするべきなのか?)
米国の規制当局は、技術的な規則違反に対する罰則を緩和しており、小さくとも重要なリスクが見過ごされてしまうのではないかという懸念が高まっています
