Pricing credit risk
The growth of the credit derivatives market has meant that Merton models are increasingly being used as a means of pricing both bonds and credit default swaps. Kate Birchall and Peter Zeitsch of ANZ Investment Bank analyse the evolution of these models
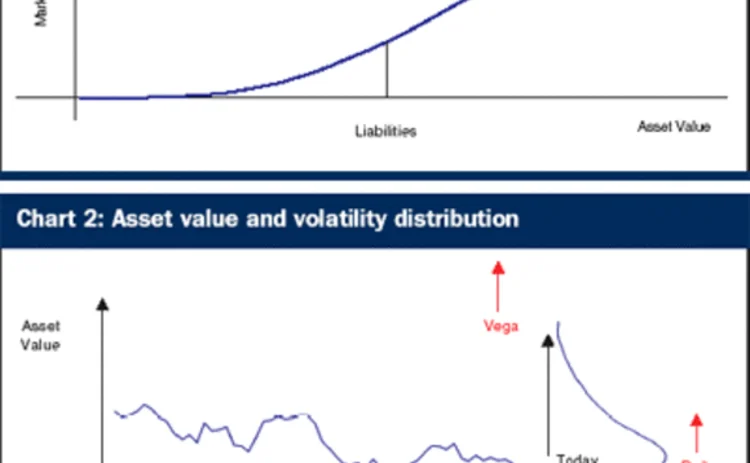
The measurement of credit risk is one of the most active areas of modern finance. The advent of credit derivatives has heightened the need to capture credit exposures even further. In 1974, the publication of Robert Merton’s academic paper1 introduced a new way of analysing corporate debt by linking it to a company’s market capitalisation, thereby quantitatively measuring credit risk. Effectively
コンテンツを印刷またはコピーできるのは、有料の購読契約を結んでいるユーザー、または法人購読契約の一員であるユーザーのみです。
これらのオプションやその他の購読特典を利用するには、info@risk.net にお問い合わせいただくか、こちらの購読オプションをご覧ください: http://subscriptions.risk.net/subscribe
現在、このコンテンツを印刷することはできません。詳しくはinfo@risk.netまでお問い合わせください。
現在、このコンテンツをコピーすることはできません。詳しくはinfo@risk.netまでお問い合わせください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(ポイント2.4)に記載されているように、印刷は1部のみです。
追加の権利を購入したい場合は、info@risk.netまで電子メールでご連絡ください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
このコンテンツは、当社の記事ツールを使用して共有することができます。当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(第2.4項)に概説されているように、認定ユーザーは、個人的な使用のために資料のコピーを1部のみ作成することができます。また、2.5項の制限にも従わなければなりません。
追加権利の購入をご希望の場合は、info@risk.netまで電子メールでご連絡ください。
詳細はこちら 市場
How hedge funds ‘hooked’ on carry fuelled Europe rates mayhem
Short-volatility traders with ‘weak hands’ may have created a market that breaks easily under stress
NAICの提案は、保険会社の投資に対するより広範な監視を示唆している
米国の生命保険各社は、資産担保証券に関する資本規制の改正案に反対の姿勢を示しました
フランスでの騒動を受け、ヘッジファンドがユーロの下落を狙っている
市場の混乱により、EUR/USDのエキゾチック商品の需要が高まり、ユーロの長期ボラティリティが上昇しています
銀行によるFVAの管理方法については、意見の一致がほとんど見られない
リスク・ベンチマーキング:ディーラーの大半は、資金調達調整において依然として複数の手法を組み合わせています
スワップスプレッドの変動により、米国の企業はロックの見直しを迫られている
スワップスプレッドの変動により、発行体は、発行前のヘッジにおいて、スワップによるロックから、よりコストのかかる米国債ロックへの切り替えを検討しています。
Trading platforms evolve for a cross-asset market
As trading becomes increasingly cross-asset, platforms are evolving to deliver consistent workflows, connectivity, intelligence and end-to-end execution efficiency

データによると、セルサイドは「濁ったCSA」をめぐる争いで劣勢にいることが示されている
リスク・ベンチマーキングの調査によると、バイサイドにおいて担保の柔軟性を求める動きが強まっていることが明らかになりました
マッコーリー、イラン情勢をめぐる2022年の対応策を発表
市場の変動と価格の不安定さが、コモディティ取引会社を厳しい試練にさらしています