Quant Finance Master’s Guide 2017
Welcome to Risk.net’s guide to the world’s leading quantitative finance master’s programmes
Click on universities in the table below for full course details. If the table is not displaying properly, click here for a pop-out version
Risk.net’s inaugural guide to the world’s leading quantitative finance master’s programmes is the first comprehensive work of its kind. It is aimed at students who want to become the quants of the future – as well as those who create the jobs they’ll end up doing.
The project also seeks to capture the changing nature of the quantitative finance industry, and the evolving skill set required to join it. On the sell side, the profession has fragmented almost beyond recognition, testing the definition of ‘quant’ for most banks; others now see the buy side as the place to be.
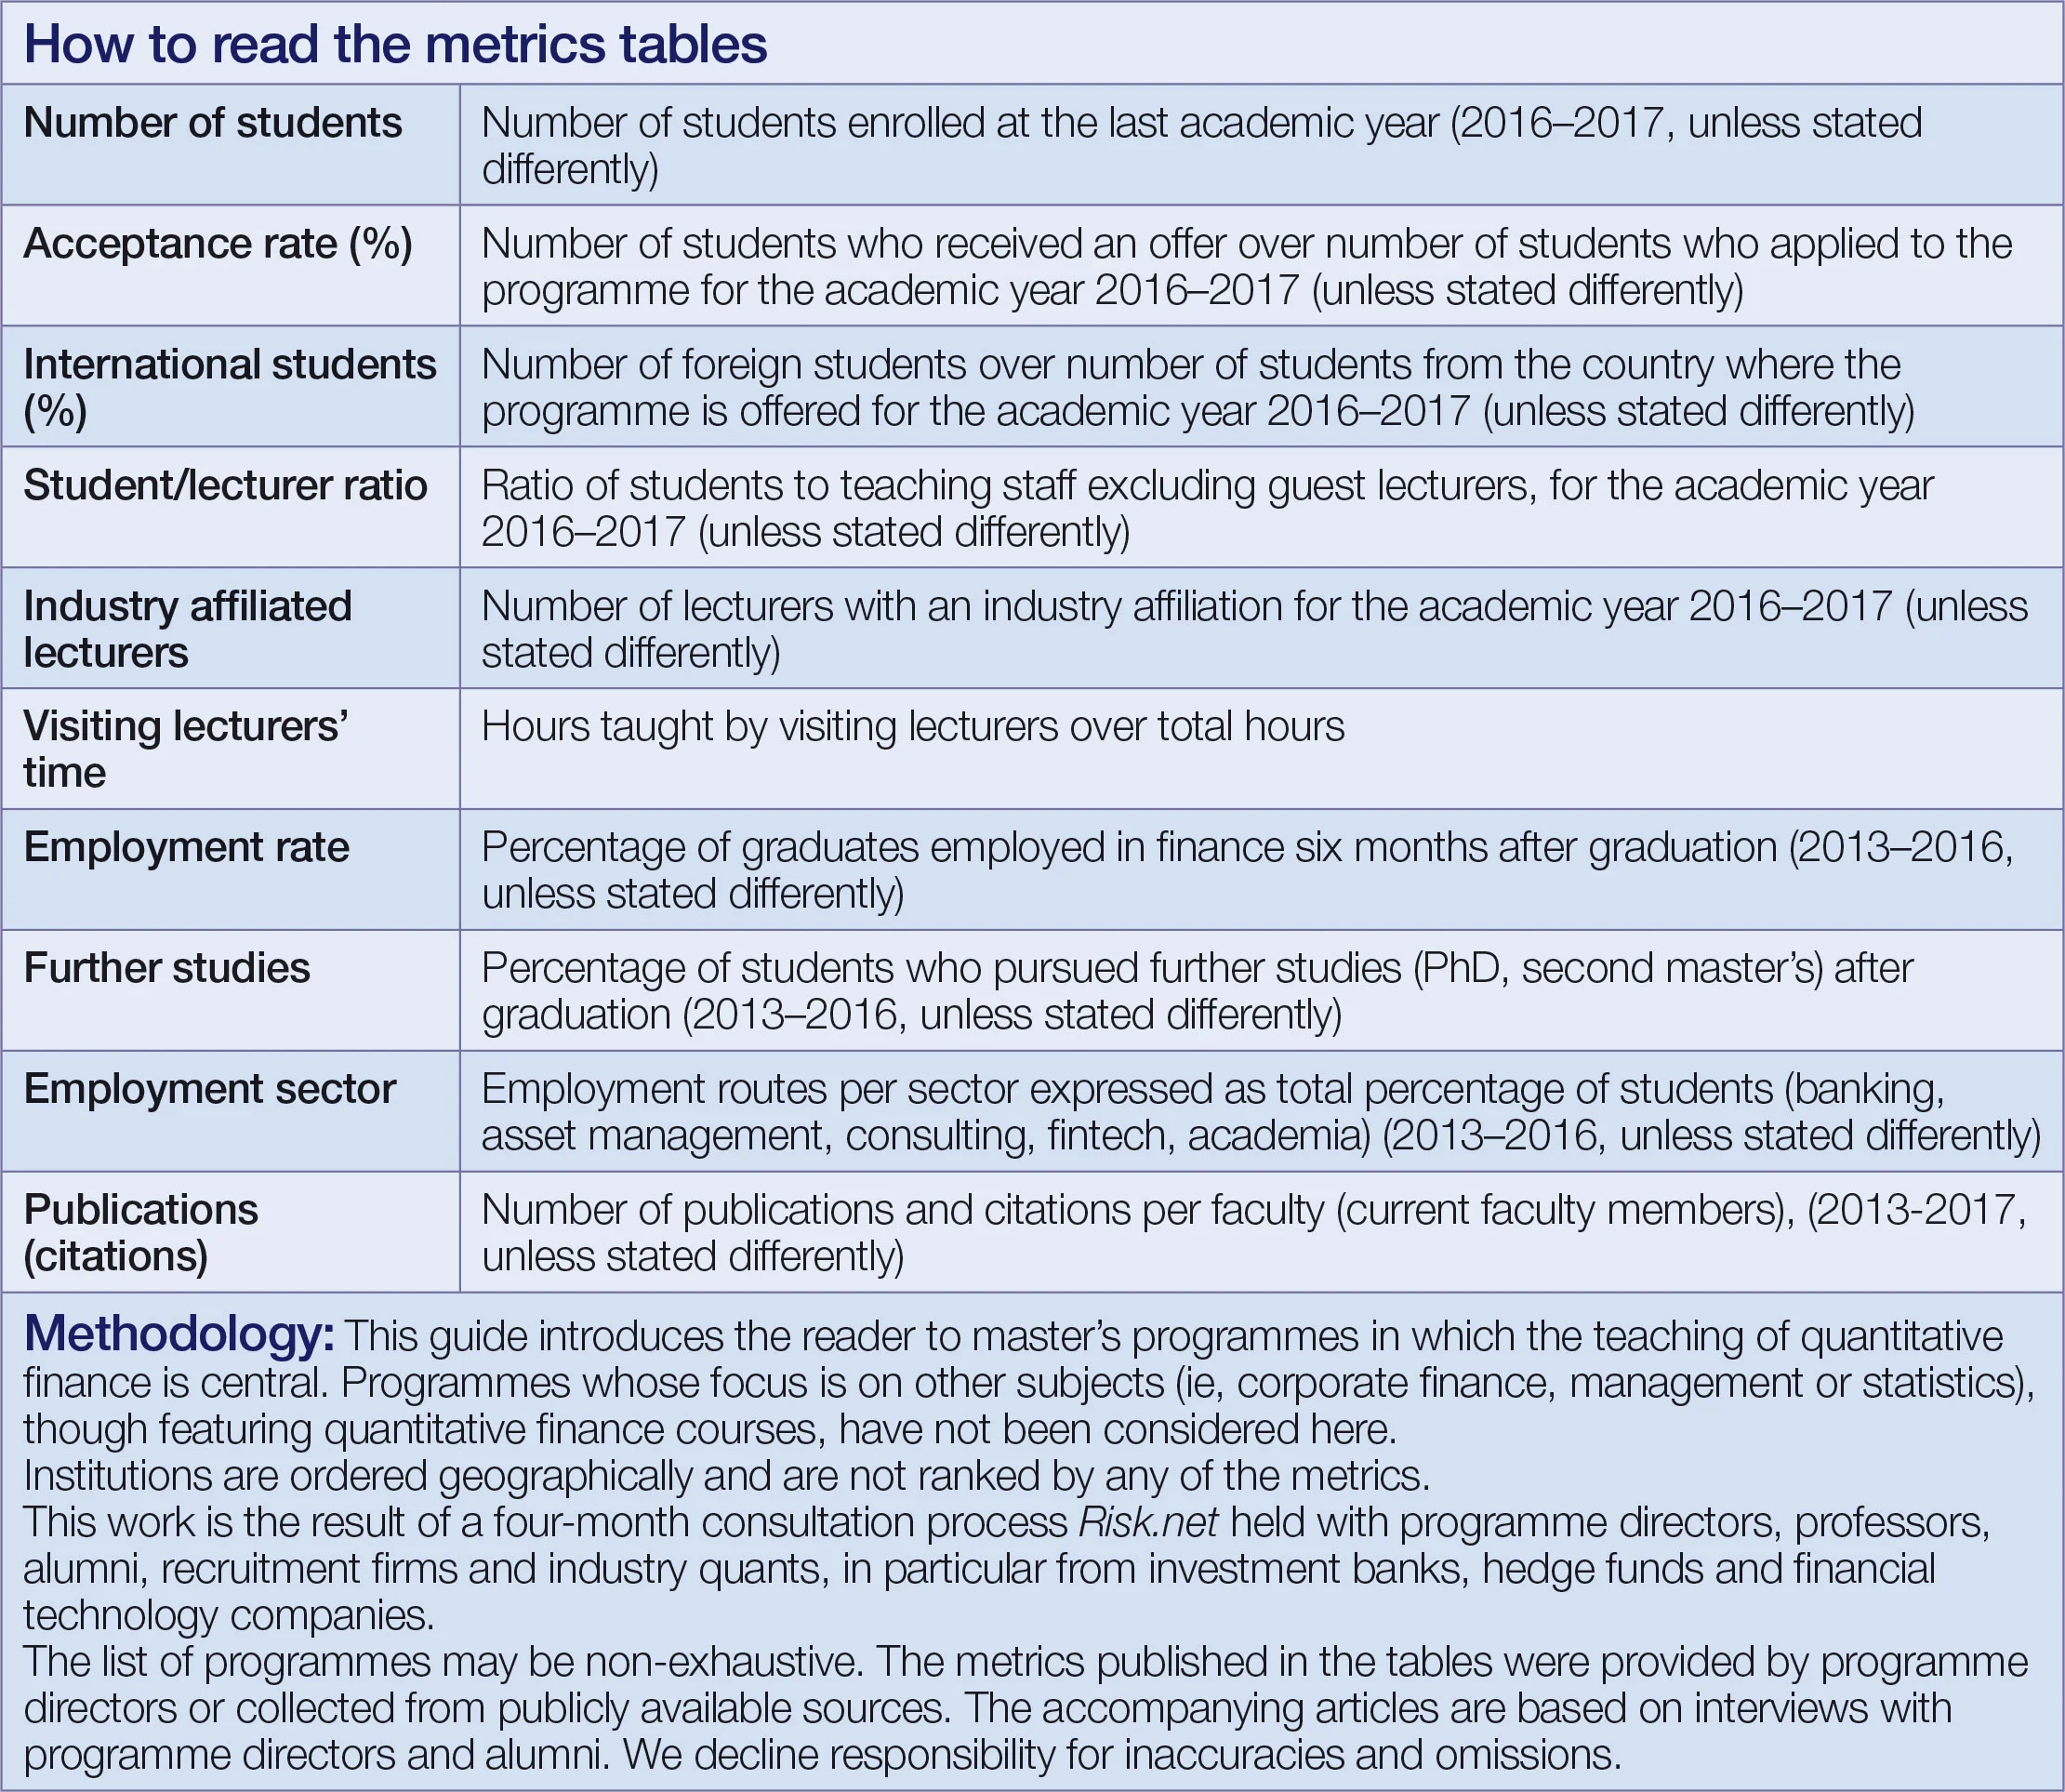
Our survey highlights common trends in the introduction of new courses, consistent with changing market requirements. But it also seeks to highlight how programmes develop their own distinctive features. As well as reporting metrics on students, their lecturers, and employability, we interviewed programme directors and alumni to provide the reader with comments and opinions that statistics alone could not communicate.
Collecting data has been facilitated by the helpfulness of faculty administrators and programme directors, for which we are grateful. In some cases, certain figures were not available, or those contacted – notably the London School of Economics, King's College London and the National University of Singapore – were unwilling or unable to provide metrics.
We initially sought to consider metrics on graduates’ salaries before and after completing a master’s, but ultimately decided not to due to the difficulty in verifying statistics and achieving a meaningful comparison between different countries and markets – and because some countries’ privacy laws impede their collection outright.
The guide is not intended to be read as a ranking of the various programmes on offer; Risk.net bears no responsibility for exceptions, oversights or omissions. The guide should not be relied on for advice – but at the very least, we hope it proves helpful to would-be master’s students, their teachers, and their future employers.
Research and reports: Sebastian Day and Alina Haritonova
Americas
Baruch College, City University of New York
University of California, Berkeley
Boston University
Carnegie Mellon University
University of Chicago
Columbia School of Engineering
Columbia University
Massachusetts Institute of Technology
NYU Courant Institute
NYU Tandon School of Engineering
Princeton University
Rutgers University
Stony Brook University
University of Washington
University of Toronto
University of Waterloo
IMPA
Europe
City, University of London
Imperial College London
Imperial College Business School
King’s College London
LSE
University of Oxford
University of Warwick
University of York
Bocconi University
University of Bologna
University of Florence
University of Turin
EISTI
Paris Diderot University
Pierre and Marie Curie University
University of Amsterdam
Erasmus University Rotterdam
EPFL
ETH Zurich/University of Zurich
WU (Vienna University of Economics and Business)
University of Leuven
University of Copenhagen
Technical University of Munich
Asia-Pacific
University of Sydney
Hong Kong University of Science and Technology
Maharishi University of Information Technology
National University of Singapore
This guide is the third part of a series on the future of quantitative finance, part of Risk’s 30th anniversary coverage. The first part, an opinion piece from UBS’s Gordon Lee, is available here. The second part, a feature on the changing role of the quant, is available here.
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@risk.net or view our subscription options here: http://subscriptions.risk.net/subscribe
You are currently unable to print this content. Please contact info@risk.net to find out more.
You are currently unable to copy this content. Please contact info@risk.net to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@risk.net
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@risk.net
More on Risk management
Eurex product co-head departs
Zubin Ramdarshan’s exit comes after exchange CEO Robbert Booij confirms departure
Off the grid? Dealers mull XVA cloud shift
Risk Benchmarking: 69% of European banks still run core XVA calculations predominantly on-premises, and 75% of global dealers
Banks want AML data upgrade to complement US regulatory reform
FinCEN’s proposed overhaul sparks debate on whether it will lead to smarter or weaker supervision

Swiss franc loan losses are a grey rhino for EU consumer finance
Impact on Polish banks exposed a blind spot on modelling legal risk that has wider implications, says mBank CRO Marek Lusztyn

CROs urged to use ‘creative’ stress tests for interconnected risks
Risk Live Asia: AI, cyber security and geopolitics mean faster shock transmission across risk types
Trading platforms evolve for a cross-asset market
As trading becomes increasingly cross-asset, platforms are evolving to deliver consistent workflows, connectivity, intelligence and end-to-end execution efficiency

Industry pushes EU exchanges to solve equity post-trade frictions
Deutsche Bank, Goldman Sachs and JP Morgan join calls for mandatory cash CCP interoperability

US Treasury clearing: competition, choice and readiness move to the fore
US Treasury clearing mandates and market reforms are reshaping clearing models, risk transfer and market infrastructure ahead of key implementation milestones