
Counterparty risk
Major US banks’ equity collateral surges to record $140bn
Stocks overtake Treasuries as fourth-largest OTC collateral type


UK banks add £7.4bn of CCR RWAs
Barclays and Standard Chartered drive counterparty credit risk surge in Q1
ING tops EU peers with hedge-heavy CVA charges
Bank’s €59.4bn CVA hedges dominated by non-CDS instruments
Top 10 op risks 2026: Cyber stays top, AI risk enters at fifth
Third-party and outsourcing risk climbs to third; fraud and fincrime edge out geopolitical risk

Record $95bn in equities sits with US banks as OTC margin
Stocks on par with US Treasuries in top dealers’ collateral trove
SS&C Algorithmics: winner’s interview with Curt Burmeister
SS&C Algorithmics wins three categories in this year’s Markets Technology Awards in addition to Technology vendor of the year at the Risk Awards
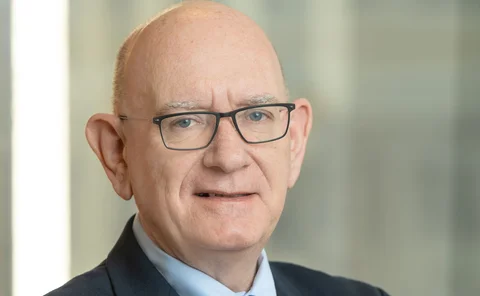
Lifetime achievement award: Dennis McLaughlin
Risk Awards 2026: When the stakes are systemic, ex-Princeton prof is never far away

FICC to launch new default fund before UST repo clearing mandate
Clearing members expected to welcome FICC’s plans to separate loss mutualisation from margin
FICC takes record bite from MMF repo investments
Funds shift cash from the Fed’s ON RRP as cleared repos hit $1.11trn
Large US banks pile up CVA charges amid tariff shock
JP Morgan’s CVA risk-weighted assets saw largest jump in second quarter since Covid-19
Is the Netherlands the EU’s main source of counterparty risk?
Experts surprised by results of exploratory scenario in 2025 ECB stress-test

Danske shrinks CVA capital charges 44% after hedge revamp
Credit protection buying spree helps cut capital requirements to lowest level since 2014
Softer DFAST market shock favours Goldman but confounds comparability
Tweak to trading book test reveals widening gap between bank and Fed loss forecasts
One to watch: Fenergo
Energy Risk Awards 2025: SaaS firm brings digitalised counterparty management to energy and commodities
Till def(ault) do us part: reassessing counterparty risk between global systemically important banks and central counterparties
The authors investigate how far liquidity at G-SIBs may be available to CCPs prior to a G-SIB resolution beginning and before a forced closeout is necessary, allowing the G-SIB to continue trading with a CCP until a payment default occurs.
A peek under the hood of Canadian banks’ new CVA machine
Disclosures from the country’s top dealers offer first glimpse of how FRTB reforms can reshape capital gauge for potential losses on derivatives
Basel tweak may weaken counterparty hedging, industry warns
Proposed technical revision risks dissuading bespoke CDSs and guarantees covering derivatives exposures

Large banks safer for CCPs than they get credit for
Plentiful pre-positioned liquidity softens the blow of resolution, new research argues
US MMFs clear record one-third of repos via FICC
Trades executed through sponsored access hit a $865 billion high at end-2024

Dissecting initial margin forecasts: models, limitations and backtesting
The authors demonstrate that initial margin is not value-at-risk, but its approximation, and suggest a generic backtesting and verification framework that accommodates both forecasting limitations and existing models.

RBC’s CVA risk charges swell 42% in first year under FRTB
Bloating RWAs contrast with declines at peers employing new standardised approach