Sympathy for the Dimon
A lack of confidence is hobbling bank stocks – and the implications go beyond valuations
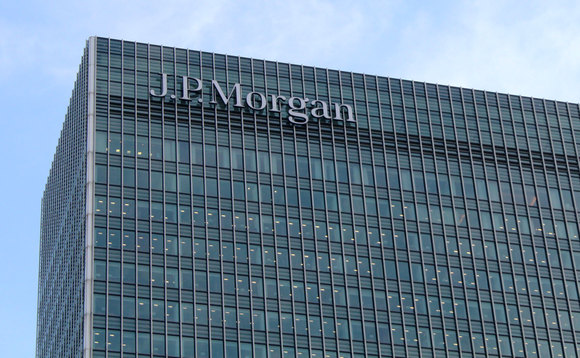
Poor Jamie Dimon. No, wait – hear me out. You have to feel for the guy. A little bit, at least. Over the course of 2015, JP Morgan delivered a 10.3% return on equity (ROE), according to Bloomberg, on the back of a record $24.4 billion in net income. Only UBS and Wells Fargo, among other big European and US banks, managed to post a double-digit ROE.
But as soon as 2016 arrived, the bank's stock started falling. By February 11, it had dropped 19.7% – one of the victims of a sector-wide sell-off that raised concerns about Deutsche Bank's solvency and sparked talk of a new systemic crisis.
There are many ways to explain a falling stock price, of course – particularly for a bank, and particularly during a period of macroeconomic uncertainty. Equity analysts sometimes point at regulation: the new environment, with multiple rules that are still in flight, has "robbed investors of any confidence in these stocks", says one. "I think the volatility has a lot to do with regulatory risk," says another.
At first blush, that feels sort of plausible, but it's worth taking it a bit further. What is it about regulation that might worry investors? It could be that it's harder to forecast future earnings, and without that visibility, valuations will be depressed and share prices more vulnerable to bad news.
Again, if that's the case, you'd need an impossibly cold heart not to feel for Dimon - his bank's ROE has been above 8% for the past six years, and earnings per share have increased steadily since 2008, with a single backward step in 2013. Surely, that deserves a bit more belief? In his letter to shareholders last year, the JP Morgan chief executive said regulatory uncertainty made it "understandable that people would pay less for our earnings than they otherwise might pay."
This isn't just about one bank's cruelly suppressed price/earnings ratio, though. The bigger worry is that fragile stocks, where the upside is capped by a lack of conviction, could end up in a terminal nosedive. Regulators argue this should not be possible - banks are less risky and more robust than at any time in recent history - so the downside should be floored as well. As Keynes had it, though: "Markets can remain irrational longer than you can remain solvent."
Ultimately, all of this probably has more to do with interest rates, inflation and economic growth than it does with the calibration of the leverage ratio, or plans to rein in the use of capital models. But whatever the cause, the lesson is the same: regulators need banks to be both strong and successful, and a world in which they are not receiving recognition for their success – even if only relative success – is a dangerous one.
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@risk.net or view our subscription options here: http://subscriptions.risk.net/subscribe
You are currently unable to print this content. Please contact info@risk.net to find out more.
You are currently unable to copy this content. Please contact info@risk.net to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@risk.net
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@risk.net
More on Risk management
CROs urged to use ‘creative’ stress tests for interconnected risks
Risk Live Asia: AI, cyber security and geopolitics mean faster shock transmission across risk types
Trading platforms evolve for a cross-asset market
As trading becomes increasingly cross-asset, platforms are evolving to deliver consistent workflows, connectivity, intelligence and end-to-end execution efficiency
Industry pushes EU exchanges to solve equity post-trade frictions
Deutsche Bank, Goldman Sachs and JP Morgan join calls for mandatory cash CCP interoperability
US Treasury clearing: competition, choice and readiness move to the fore
US Treasury clearing mandates and market reforms are reshaping clearing models, risk transfer and market infrastructure ahead of key implementation milestones
Barclays built a system to spot AI agents that might go rogue
Research setup ‘reads the mind’ of LLM-based agents and flags if they’re about to do something risky
Op risk data: EFG takes a bath for two decades of money laundering
Also: Deepfake voice clone cons Intesa division; key couple of cryptocurrency hacks. Data by ORX News
Managing risk to accelerate agentic AI value creation
Banks can accelerate agentic AI adoption by aligning each use case’s risks, controls and capabilities, enabling safe, accountable and value-driven deployment
One legal entity. Multiple IDs. Three business risks.
How fragmented entity IDs undermine risk, compliance and revenue decisions