Climate risk – A new normal
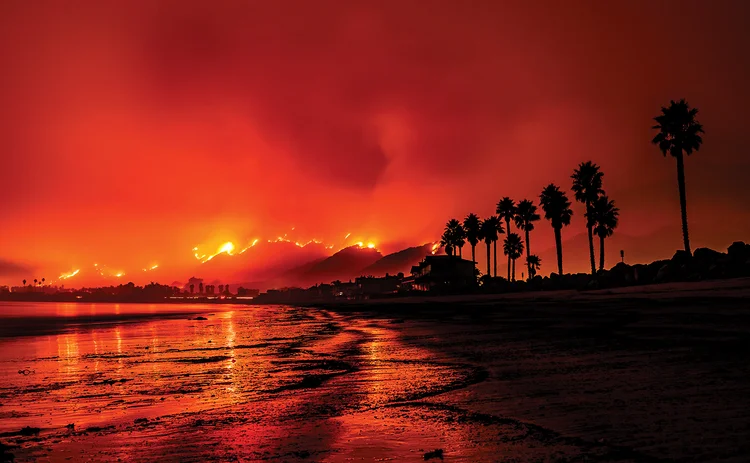
The past two full years – 2017 and 2018 – were the most costly back-to-back years on record for weather-related disasters say insurance companies, with economic losses exceeding $650 billion. Moreover, 2018 was the fourth costliest year on record for weather-related events, even though there were no events on the scale of hurricanes Katrina in 2005, and Harvey, Irma and Maria in 2017.
Experts believe 2018 represents a ‘new normal’, when a large number of relatively small natural disasters added up to substantial losses.
Trying to ascertain how many of these events are the result of global climate change, and how many would have happened regardless, is extremely challenging, but historical data can certainly be applied to show that the frequency of severe weather events has increased in recent years.
Investment firm Schroders estimates global economic losses from climate change could reach $23 trillion per year in the long term if action isn’t taken. That’s almost four times the impact of the 2008 financial crisis.
But for individual firms, trying to quantify the risk of physical climate change on their assets, infrastructure, businesses and supply chains is no easy feat. While many firms are used to managing weather risk on an annual or seasonal basis, managing the long-term, ever-increasing effects of climate change requires a very different approach. It is something many firms are grappling with now, not least because shareholders and investors require greater transparency on it.
This report explores how corporates – and the banks that invest and lend to them – are approaching this new discipline. It also examines developments in disclosure – particularly those stemming from the guidelines of the Task Force on Climate-related Financial Disclosures.
However, climate risk is not just about the economic losses caused by severe weather events, rising sea levels and higher temperatures. It is also about trying to understand how the transition to a low-carbon economy might affect businesses. Firms involved in the production of fossil fuels will be particularly affected by policy efforts to reduce carbon emissions and curb demand for the highest-polluting fuels.
Several banks have already started to model transition risk in their investment and lending portfolios although, again, this is a discipline in its infancy (see page 12).
While there are many different approaches to modelling this risk, most agree that the long time horizon and the sheer number of variables and possibilities mean that a scenario approach makes most sense.
There is also widespread agreement that assessing and managing climate risk will require the co-operation of enterprise risk and business risk managers, but it will also require them to work alongside environmental and social responsibility teams. While climate risk is identified as a top risk at many firms now, it needs to move beyond the level of public relations and ethics to a quantifiable business risk that can be communicated in a transparent and standardised way.
We hope this report provides invaluable information to companies as they embark on this journey. As ratings agency Standard & Poor’s noted at last year’s UN Climate Change Conference: “Climate change has already started to alter the functioning of our world.”
コンテンツを印刷またはコピーできるのは、有料の購読契約を結んでいるユーザー、または法人購読契約の一員であるユーザーのみです。
これらのオプションやその他の購読特典を利用するには、info@risk.net にお問い合わせいただくか、こちらの購読オプションをご覧ください: http://subscriptions.risk.net/subscribe
現在、このコンテンツを印刷することはできません。詳しくはinfo@risk.netまでお問い合わせください。
現在、このコンテンツをコピーすることはできません。詳しくはinfo@risk.netまでお問い合わせください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(ポイント2.4)に記載されているように、印刷は1部のみです。
追加の権利を購入したい場合は、info@risk.netまで電子メールでご連絡ください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
このコンテンツは、当社の記事ツールを使用して共有することができます。当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(第2.4項)に概説されているように、認定ユーザーは、個人的な使用のために資料のコピーを1部のみ作成することができます。また、2.5項の制限にも従わなければなりません。
追加権利の購入をご希望の場合は、info@risk.netまで電子メールでご連絡ください。
詳細はこちら リスク管理
欧州では、FRTBがXVAヘッジに噛みつくと見込まれている
リスク・ベンチマーキング:欧州のディーラーの3分の1が、新たな市場リスク規制がヘッジに大きな影響を及ぼすことを懸念しています
ノンバンクディーラーたちは、FICCデフォルト基金の再編について再考を求めている
マージンを分別することにより銀行の資本は減少しますが、ノンバンク金融機関は、不釣り合いなリスク分担を強いられると警告しています。
信用リスクモデリングにおけるAIには、なぜハイブリッドのアプローチが最も適しているのか
AIはモデルが四半期報告書以上の情報を把握するのを支援していますが、CROによると、ガバナンスが完全な自動化を妨げているとのことです
ユーレックスの商品部門共同責任者が退任
取引所のCEOであるロバート・ブイ氏が退任を明らかにしたことを受け、ズビン・ラムダルシャン氏も退任することになりました。
オフ・ザ・グリッド? ディーラー各社がXVAのクラウド移行を検討中
リスク・ベンチマーキング:欧州の銀行の69%は、依然としてコアとなるXVAの計算を主にオンプレミスで行っており、世界のディーラーの75%は
銀行各社は、米国の規制改革を補完するため、AMLデータの更新を求めている
FinCENが提案した抜本的な改革案をめぐり、これが監督体制をより賢明なものにするのか、それとも弱体化させるのかという議論が巻き起こっています。

スイスフラン建てローンの損失は、EUの消費者金融業界にとっての灰色のサイである
mBankのCROであるマレク・ルシュティン氏は、ポーランドの銀行への影響が、法的リスクのモデリングにおける盲点を浮き彫りにし、それがより広範な影響を及ぼしていると述べています。

CROに対し、相互に関連するリスクに対して「独創的な」ストレステストの実施が求められている
Risk Live Asia:AI、サイバーセキュリティ、地政学的な要因により、リスクの種類を問わずショックの波及が加速しています