Pursuing alpha
Despite remaining unchanged since classical times, it seems the first two letters of the Greek alphabet are being reversed these days. At least that's what some leading international dealers are saying.
They reckon that certain popular structures such as constant maturity swap steepeners and range accruals, which were previously sold as yield-enhancing structures, are now so common that they represent market convention. That means they are no longer the alpha-generators of choice.
Today, they represent the market benchmark, effectively beta, dealers say. That's a strange concept given that each structure is different in terms of maturity, benchmark curve, leverage and so on.
Nevertheless, large dealers believe the new source of alpha comes from proprietary trading models, which are rules-based, established as indexes and sold to clients as structured products. By offering this new breed of so-called alpha-generating fixed-income products, dealers have apparently put themselves on a collision course with their hedge funds clients from which they make significant sums of money as trading counterparts, and to a lesser extent by acting as their prime brokers.
The argument goes that if a major bank can roll out proprietary trading models to its clients in a transparent manner, why would a customer pay the typical 2% asset-linked, 20% performance fees required by a black box hedge fund that, after all, could well be deploying exactly the same trading strategy? Sure, top hedge fund managers will probably outperform an algorithmic trading strategy, but there are hundreds of hedge funds that won't.
There is a loose analogy here with the early development of constant proportion debt obligations (CPDOs), which automatically had to roll their positions despite the market conditions not necessarily being optimal to do so. Now, the same dealers that are touting managed CPDOs as a solution to that problem - they say a skilled manager can optimise the market timing of the roll - are nonetheless offering systematic index trades that may or may not suffer as they revolve into the next period of the contract.
- Christopher Jeffery.
コンテンツを印刷またはコピーできるのは、有料の購読契約を結んでいるユーザー、または法人購読契約の一員であるユーザーのみです。
これらのオプションやその他の購読特典を利用するには、info@risk.net にお問い合わせいただくか、こちらの購読オプションをご覧ください: http://subscriptions.risk.net/subscribe
現在、このコンテンツを印刷することはできません。詳しくはinfo@risk.netまでお問い合わせください。
現在、このコンテンツをコピーすることはできません。詳しくはinfo@risk.netまでお問い合わせください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(ポイント2.4)に記載されているように、印刷は1部のみです。
追加の権利を購入したい場合は、info@risk.netまで電子メールでご連絡ください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
このコンテンツは、当社の記事ツールを使用して共有することができます。当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(第2.4項)に概説されているように、認定ユーザーは、個人的な使用のために資料のコピーを1部のみ作成することができます。また、2.5項の制限にも従わなければなりません。
追加権利の購入をご希望の場合は、info@risk.netまで電子メールでご連絡ください。
詳細はこちら 規制
BISのエルナンデス・デ・コス氏、AI、ノンバンク・リスク、トークン化について語る
ゼネラルマネージャーが、BISが複雑な世界情勢をどのように乗り切っているかについて語りました

「欧州版SEC」は成長の特効薬ではない
EUの政策立案者たちは、単一かつ一元化された監督機関が欧州経済の活性化につながることを期待していますが、批判の声も高まっています
IMAの導入には、FRTBの恒久的な改革が不可欠であると考えられている
6月に認められた一時的な措置は、欧州における内部モデルの利用を促進する上でほとんど効果を上げていません
次回のクレディ・スイスが「円滑に」破綻するよう確保するには
過去の銀行破綻において「リビングウィル」が無視されたとの批判を受け、規制当局は破綻処理規則の改正を計画しています
アジアの企業は、USTの清算義務の適用除外に期待を寄せている
域外適用に関する緩和を期待しているものの、アジア太平洋地域の企業の51%は、まだコンプライアンス・プログラムを開始していません
すでにFRTBの対象となっている一部の銀行は、モデリング要件の緩和を期待している
Risk Live:BMOとUBSはSAを採用しましたが、まだ規制当局がより緩やかな米国の規則に従う可能性もあると考えています
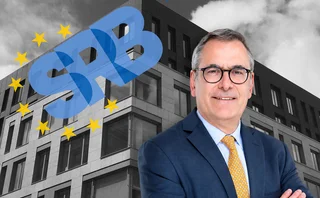
SRBのトップは、「規制者たちは次なるクレディ・スイスのような事態によりよく備えている」と述べる
FSBは国際間協力に関する指針を強化していますが、EUにはさらなる相互支援が必要です
柱から柱……そしてポストへ:欧州のオペリスクの行方は?
専門家たちは、DORAの知見を踏まえた、強化された第2の柱の要件の方が、画一的な第1の柱よりも有用であると考えている