

In-depth introduction: Japan
Senior officials at the BoJ and JFSA speak to Risk.net about QE, Basel III and more
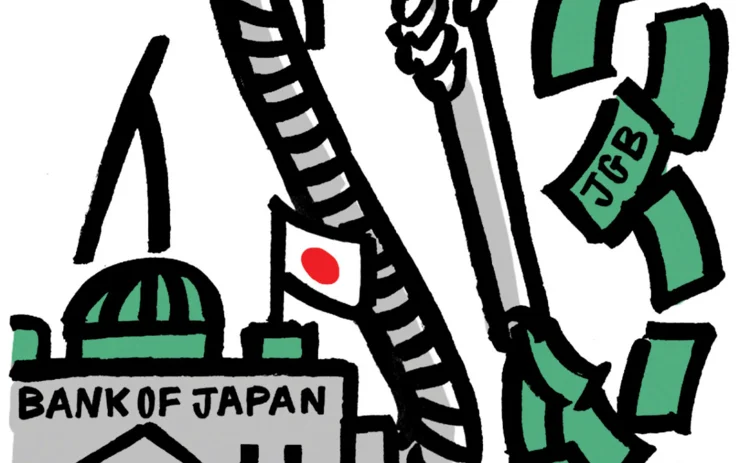
Japan's finance ministry plans to issue new bonds this year worth a total of ¥36.9 trillion ($309.1 billion). The country's central bank, meanwhile, is planning to buy ¥80 trillion of the debt, under its expanded quantitative easing programme. It's a bold attempt to support the economy and help hit a 2% inflation target, but it has some risks – not least that the Japanese government bond (JGB) market might grind to a halt if the Bank of Japan (BoJ) hoovers up all the available supply.
The BoJ's deputy governor, Hiroshi Nakaso, doesn't seem the type to take fright easily. The BoJ will hit its 2% target, he insists, and it will continue buying bonds until it has achieved its goal. That should come in the first half of the 2016 fiscal year, he predicts, oil prices permitting.
Nakaso admits the depth of the JGB futures market has suffered since the central bank expanded its bond-buying programme in October last year – as demonstrated by analysis the BoJ published in August – but not to the extent that quantitative easing will need to be reined in, he says.
Over at Japan's Financial Services Agency (FSA), Shunsuke Shirakawa is a similarly forthright character. The deputy commissioner for international affairs is calling for the Basel Committee on Banking Supervision to help clarify the status of the counter-cyclical capital buffers that members states are obliged to introduce as part of Basel III. Supervisors are free to set these buffers at 0% – as the FSA will, says Shirakawa, while economic growth is still fragile – but banks that are active internationally will be subject to the buffers of every country in which they have exposure, and many have not yet implemented them. Shirakawa wants the relevant information for each state to be published on the Basel Committee's site.
In Europe, things are made more complicated by the fact that some member states of the EU are not members of the Basel Committee and may, or may not, be required to introduce the buffers. Clarification is "urgently needed", Shirakawa says.
The BoJ will hit its 2% target, he insists, and it will continue buying bonds until it has achieved its goal
In addition, he mentions the FSA is considering the possibility of using Japan's deposit insurance system as a backstop for central counterparties – an intriguing idea, but one that would need parliamentary approval – and also lifts the lid on a cross-border dispute with the Commodity Futures Trading Commission.
There are some concerns shared by both men. As Japanese banks expand internationally, they must ensure they have stable funding in currencies that match their new assets, they warn – and both also strike a cautionary note on expanding bank capital requirements. Once the current programme of work is complete, says the BoJ's Nakaso, "we need to ensure the right communication with banks and tell market participants that additional prudential regulations will not be introduced for some time".
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@risk.net or view our subscription options here: http://subscriptions.risk.net/subscribe
You are currently unable to print this content. Please contact info@risk.net to find out more.
You are currently unable to copy this content. Please contact info@risk.net to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@risk.net
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@risk.net
More on Regulation
Competitiveness mandate for Esma faces uphill battle
European Parliament offers last chance to force Esma to take more nuanced approach

Europe expects FRTB to bite on XVA hedges
Risk Benchmarking: One-third of European dealers fear new market risk rules will have major effect on hedges
Burning ambition: will Europe join the US in setting fire to the rules?
As the US dismantles post-crisis regulations, some think Europe will follow in a bid to boost economic growth
Can US perpetual futures solve their identity crisis?
Market could fall under four different regulatory categories, with sharply diverging outcomes
Banks want AML data upgrade to complement US regulatory reform
FinCEN’s proposed overhaul sparks debate on whether it will lead to smarter or weaker supervision

Industry pushes EU exchanges to solve equity post-trade frictions
Deutsche Bank, Goldman Sachs and JP Morgan join calls for mandatory cash CCP interoperability

Regulatory clarity urged for CME’s single-stock futures
SEC short selling and market access rules may hamper clearing and broker participation

Imminent US shake-up of LCR slated to include discount window
Adding Fed liquidity facility to bank regulation may help overcome stigma, raise lending capacity
