Getting stressed
To understand how much value can be lost from a position in the energy markets, we need to use measures other than value-at-risk. Brett Humphreys discusses methods for creating effective stress tests
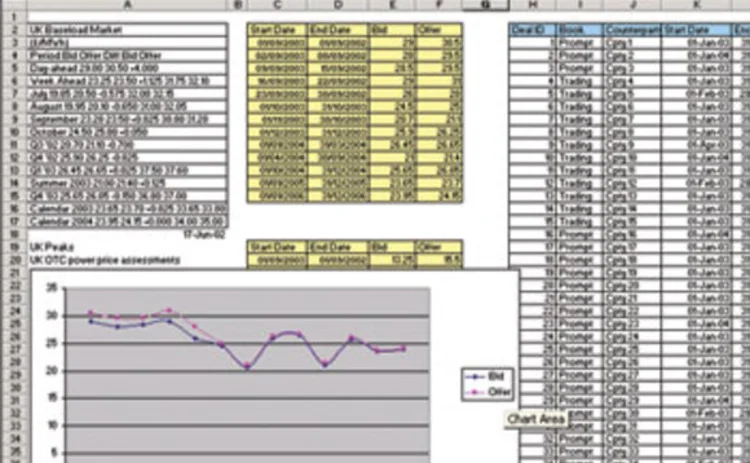
Joe Risk-Manager has a problem. Given the recent turbulence in the energy markets, senior management has realised that a simple value-at-risk (Var) measure is insufficient for measuring the risk of the firm’s portfolio. So Joe has been asked to perform stress tests on the trading portfolio.
The stress test he chose was a parallel shift of all forward curves by five standard deviations
コンテンツを印刷またはコピーできるのは、有料の購読契約を結んでいるユーザー、または法人購読契約の一員であるユーザーのみです。
これらのオプションやその他の購読特典を利用するには、info@risk.net にお問い合わせいただくか、こちらの購読オプションをご覧ください: http://subscriptions.risk.net/subscribe
現在、このコンテンツを印刷することはできません。詳しくはinfo@risk.netまでお問い合わせください。
現在、このコンテンツをコピーすることはできません。詳しくはinfo@risk.netまでお問い合わせください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(ポイント2.4)に記載されているように、印刷は1部のみです。
追加の権利を購入したい場合は、info@risk.netまで電子メールでご連絡ください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
このコンテンツは、当社の記事ツールを使用して共有することができます。当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(第2.4項)に概説されているように、認定ユーザーは、個人的な使用のために資料のコピーを1部のみ作成することができます。また、2.5項の制限にも従わなければなりません。
追加権利の購入をご希望の場合は、info@risk.netまで電子メールでご連絡ください。
詳細はこちら 市場リスク
レポ市場とFX市場、年末の金融引き締め懸念に逆行
価格高騰の懸念は和らぎ、9月のSOFRの急騰は銀行の粉飾決算の早期準備につながりました。
Market risk solutions 2023: market and vendor landscape
A Chartis Research report that examines the structural shifts in enterprise risk systems and the impact of regulations, as well as the available technology.
The new rules of market risk management
Amid 2020’s Covid-19-related market turmoil – with volatility and value-at-risk (VAR) measures soaring – some of the world’s largest investment banks took advantage of the extraordinary conditions to notch up record trading revenues. In a recent Risk.net…
ETF strategies to manage market volatility
Money managers and institutional investors are re-evaluating investment strategies in the face of rapidly shifting market conditions. Consequently, selective genres of exchange-traded funds (ETFs) are seeing robust growth in assets. Hong Kong Exchanges…
FRTB spurs data mining push at StanChart
Bank building “single golden source” of trade data in a bid to lower NMRF burden

Asian privacy laws obstruct FRTB data pooling efforts
Bank scepticism and regulatory hurdles likely to inhibit cross-border information sharing
Seizing the opportunity of transformational change
Sponsored Q&A: CompatibL, Murex and Numerix
Doubts grow over US FRTB implementation
Fragmented roll-out would price European banks “out of the market”