Podcast: Mercurio and Henrard on Libor transition and the need to involve quants early in discussions
Some derivatives products will become more complex if there are no forward rates; industry must act fast, say quants
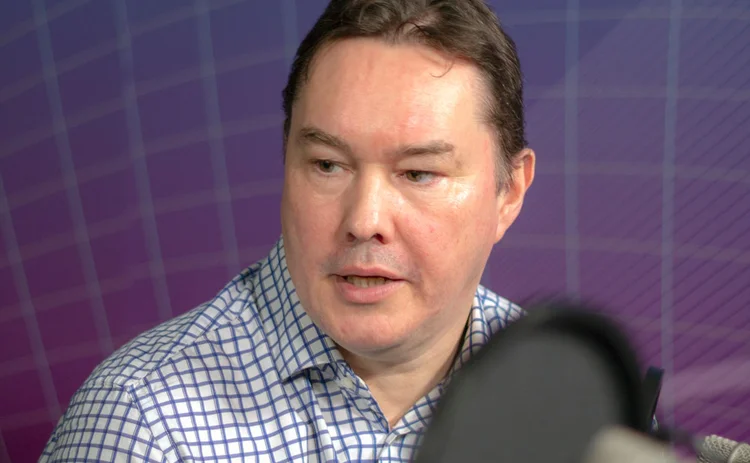
Marc Henrard, a managing partner at muRisQ Advisory, visited our London offices to record a podcast on the challenges of Libor transition as part of benchmark reform. He was joined over the phone by Fabio Mercurio, head of the quant analytics team at Bloomberg.
The derivatives industry is preparing for the death of Libor, which is most likely to happen after 2021. After this time, panel banks will no longer be required to contribute to the rate. The UK, US and Europe have already selected new overnight risk-free rates (RFRs) to replace Libor as the reference rate in new contracts, while the International Swaps and Derivatives Association is leading the derivatives industry’s efforts to develop a fallback rate for existing contracts.
Recent industry consultation found the derivatives market’s preferred fallback for contracts referencing Libor is a backward-looking term version of RFRs, which would compound daily rates in arrears, while an additional fixed spread would reflect the bank credit element inherent in Libor.
This would create some challenges for derivatives products, which are fundamentally defined based on forward rates, the quants argue.
For instance, forward rate agreements (FRAs) allow the buyer to lock in a future loan by agreeing to pay a forward rate set at the beginning of the contract. Without a forward rate, the products won’t work.
“You have to change the nature of the contract; you are not just changing the underlying rate,” says Mercurio.
He suggests one solution is to redefine an FRA as a single period swap based on a backward rate, but Henrard argues market participants need to start thinking about implementing these sorts of solutions now rather than after the fallback triggers.
“If we think fallback in arrears is the best, we should probably change the term sheet of the FRAs now before having the fallback instead of having the fallback and then, when it’s there, noticing that it’s too late to change the definitions,” he argued.
Pricing of caps and floors – which are like options on FRAs – will also become more complex, argued the quants, as the compounded-in-arrears rate is calculated based on multiple daily overnight rates over a period instead of a single Libor term rate.
“When it comes to pricing, if you have to keep track of daily changes, that is more complicated than keeping track of a single number,” says Mercurio.
Mercurio recently developed a pricing model with Andrei Lyashenko, a senior quant at consultancy Quantitative Risk Management in Chicago, to deal with these issues, but admitted the eventual changes to models and systems because of the Libor transition would be quite disruptive.
Given the complexities the transition is likely to introduce, both Mercurio and Henrard agreed quants should have been involved in the decision-making process earlier.
“In general, quants are called in later and we need to fix the issues rather than being called to be part of the conversations,” says Mercurio.
However, he adds that the introduction of complexity does keep his job more exciting – “As a quant I am also happy not to be involved too early. This means there could be more issues to address and even more job security for us – and more fun.”
Index
0:00 Introduction
1:30 Current state of Libor reform
3:23 Impact of backward-looking rate on derivatives
7:38 Products that will be impacted the most
10:43 Increase in complexity
11:16 Solution for using backward rate in FRAs
18:34 Pricing of caps and floors
24:20 Impact on structured products
32:17 Mismatch in type of term rate between currencies
37:40 Why quants should be involved early in reforms
References
- Marc Henrard (2019)
A quant opinion on Libor fallback - Lyashenko A and Mercurio F (2019)
Looking Forward to Backward-Looking Rates: A Modeling Framework for Terms Rates Replacing LIBOR
To hear the full interview, listen in the player above, or download. Future podcasts in our Quantcast series will be uploaded to Risk.net. You can also visit the main page here to access all tracks, or go to the iTunes store or Google Podcasts to listen and subscribe.
Only users who have a paid subscription or are part of a corporate subscription are able to print or copy content.
To access these options, along with all other subscription benefits, please contact info@risk.net or view our subscription options here: http://subscriptions.risk.net/subscribe
You are currently unable to print this content. Please contact info@risk.net to find out more.
You are currently unable to copy this content. Please contact info@risk.net to find out more.
Copyright Infopro Digital Limited. All rights reserved.
As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (point 2.4), printing is limited to a single copy.
If you would like to purchase additional rights please email info@risk.net
Copyright Infopro Digital Limited. All rights reserved.
You may share this content using our article tools. As outlined in our terms and conditions, https://www.infopro-digital.com/terms-and-conditions/subscriptions/ (clause 2.4), an Authorised User may only make one copy of the materials for their own personal use. You must also comply with the restrictions in clause 2.5.
If you would like to purchase additional rights please email info@risk.net
More on Markets
Hedge funds shelved yen basis bet on US deal
Funds exited USD/JPY flatteners tied to Japan’s $550bn pledge and new funding may not revive the trade
BRL bulls hold firm after Bolsonaro first-round win
Hedge funds keep USD/BRL puts ahead of election run-off as protection premiums for Lula upset soar
AI boom turns Morgan Stanley into a hot commodity
Talking Heads 2026: Data centres need long-dated power and gas hedges that only a big bank can provide
PGGM sees a chance to diversify with fourth-trigger CDSs
Dutch pension manager hopes bank demand will continue to grow for derivatives counterparty credit protection
How Quoniam boosted its sentiment strategy by adding an LLM
Upgraded system creates scores from more-informative forward-looking parts of news
The changing shape of fixed income trading
As volumes surge and electronification spreads, trading desks are rethinking how they access liquidity and the technology that supports it
Canton: has Wall Street found its blockchain?
Network and privacy behind Digital Asset spin-off’s tilt at next-gen settlement
NSE chief blames algos for India closing auction turmoil
Ashishkumar Chauhan said traders should retrain algos instead of asking Sebi to change closing auction