

UBS structures second Alpine risk capacity ‘enhancer’
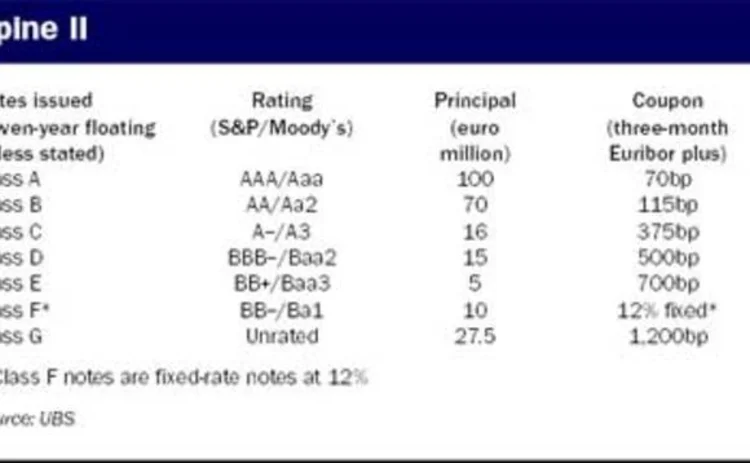
UBS has enhanced the credit risk capacity in its derivatives trading book by E1.5 billion, through an innovative managed securitisation issued in early April. The so-called Alpine II structure, based on the description of its reference pool and the ratings applicable, could save the bank between 20% and 30% of the cost of using single-name credit default swaps. It is aimed at freeing UBS’s credit limits to enable the bank to trade more derivatives volumes with key business clients, the bank claims.
コンテンツを印刷またはコピーできるのは、有料の購読契約を結んでいるユーザー、または法人購読契約の一員であるユーザーのみです。
これらのオプションやその他の購読特典を利用するには、info@risk.net にお問い合わせいただくか、こちらの購読オプションをご覧ください: http://subscriptions.risk.net/subscribe
現在、このコンテンツを印刷することはできません。詳しくはinfo@risk.netまでお問い合わせください。
現在、このコンテンツをコピーすることはできません。詳しくはinfo@risk.netまでお問い合わせください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(ポイント2.4)に記載されているように、印刷は1部のみです。
追加の権利を購入したい場合は、info@risk.netまで電子メールでご連絡ください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
このコンテンツは、当社の記事ツールを使用して共有することができます。当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(第2.4項)に概説されているように、認定ユーザーは、個人的な使用のために資料のコピーを1部のみ作成することができます。また、2.5項の制限にも従わなければなりません。
追加権利の購入をご希望の場合は、info@risk.netまで電子メールでご連絡ください。
詳細はこちら 信用リスク
Vendor spotlight: Credit lending operations, 2025
Crisil’s Credit+ platform is a modular, enterprise credit lending and operations platform on a microservices-based architecture

Vendor spotlight: Credit risk management solutions, 2025
Crisil has adopted a platform strategy that brings together its full suite of credit risk, analytics and regulatory capabilities

米銀のCROは、関税による信用リスクは「控えめ」であると見ている
Risk Live NA:利益率の低下はストレスの初期兆候ですが、シチズンズ、アライ、ピナクルの各社は貸出ポートフォリオに自信を示しています
Credit risk management solutions 2024: market update and vendor landscape
A Chartis report outlining the view of the market and vendor landscape for credit risk management solutions in the trading and banking books

Finding the investment management ‘one analytics view’
This paper outlines the benefits accruing to buy-side practitioners on the back of generating a single analytics view of their risk and performance metrics across funds, regions and asset classes

Revolutionising liquidity management: harnessing operational intelligence for real‑time insights and risk mitigation
Pierre Gaudin, head of business development at ActiveViam, explains the importance of fast, in-memory data analysis functions in allowing firms to consistently provide senior decision-makers with actionable insights
Sec-lending haircuts and indemnification pricing
A pricing method for borrowed securities that includes haircut and indemnification is introduced
XVAs and counterparty credit risk for energy markets: addressing the challenges and unravelling complexity
In this webinar, a panel of quantitative researchers and risk practitioners from banks, energy firms and a software vendor discuss practical challenges in the modelling and risk management of XVAs and CCR in the energy markets, and how to overcome them.
