Central bank reports more leverage in swaps market
The second half of 2002 saw a sharp rise in leverage in the interest rate swap market, according to the June issue of the Bank of England's Financial Stability Review.
The review also cited a growing number of hedge funds and increased volumes of securitisation – in which arrangers have an incentive to achieve the greatest possible leverage consistent with target ratings – as other possible sources of system leverage in financial markets.
コンテンツを印刷またはコピーできるのは、有料の購読契約を結んでいるユーザー、または法人購読契約の一員であるユーザーのみです。
これらのオプションやその他の購読特典を利用するには、info@risk.net にお問い合わせいただくか、こちらの購読オプションをご覧ください: http://subscriptions.risk.net/subscribe
現在、このコンテンツを印刷することはできません。詳しくはinfo@risk.netまでお問い合わせください。
現在、このコンテンツをコピーすることはできません。詳しくはinfo@risk.netまでお問い合わせください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(ポイント2.4)に記載されているように、印刷は1部のみです。
追加の権利を購入したい場合は、info@risk.netまで電子メールでご連絡ください。
Copyright インフォプロ・デジタル・リミテッド.無断複写・転載を禁じます。
このコンテンツは、当社の記事ツールを使用して共有することができます。当社の利用規約、https://www.infopro-digital.com/terms-and-conditions/subscriptions/(第2.4項)に概説されているように、認定ユーザーは、個人的な使用のために資料のコピーを1部のみ作成することができます。また、2.5項の制限にも従わなければなりません。
追加権利の購入をご希望の場合は、info@risk.netまで電子メールでご連絡ください。
詳細はこちら 規制
理事会、AquisとBMEをESMAの監督対象から外す方針
情報筋によると、ドイツ取引所を適用除外とするドイツ側の動きにより、他の3社も巻き込まれているとのことです
なぜ破綻処理計画を骨抜きにするのは良くないのか
銀行の破綻は避けられないものですが、銀行危機はそうではありません
BISのエルナンデス・デ・コス氏、AI、ノンバンク・リスク、トークン化について語る
ゼネラルマネージャーが、BISが複雑な世界情勢をどのように乗り切っているかについて語りました

「欧州版SEC」は成長の特効薬ではない
EUの政策立案者たちは、単一かつ一元化された監督機関が欧州経済の活性化につながることを期待していますが、批判の声も高まっています
IMAの導入には、FRTBの恒久的な改革が不可欠であると考えられている
6月に認められた一時的な措置は、欧州における内部モデルの利用を促進する上でほとんど効果を上げていません
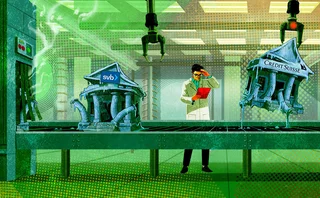
次回のクレディ・スイスが「円滑に」破綻するよう確保するには
過去の銀行破綻において「リビングウィル」が無視されたとの批判を受け、規制当局は破綻処理規則の改正を計画しています
アジアの企業は、USTの清算義務の適用除外に期待を寄せている
域外適用に関する緩和を期待しているものの、アジア太平洋地域の企業の51%は、まだコンプライアンス・プログラムを開始していません
すでにFRTBの対象となっている一部の銀行は、モデリング要件の緩和を期待している
Risk Live:BMOとUBSはSAを採用しましたが、まだ規制当局がより緩やかな米国の規則に従う可能性もあると考えています